Insurance Savings and News You Can Use
Join the Conversation!

David Ross

Recent Posts

Contractor Insurance: The Complete Guide for PA Contractors & Construction Firms

Posted by David Ross on Tue, Oct 13, 2026

Call us for the best insurance for contractors in Philadelphia, Pittsburgh, Erie, Lancaster, York, Harrisburg, Reading, Allentown and throughout PA

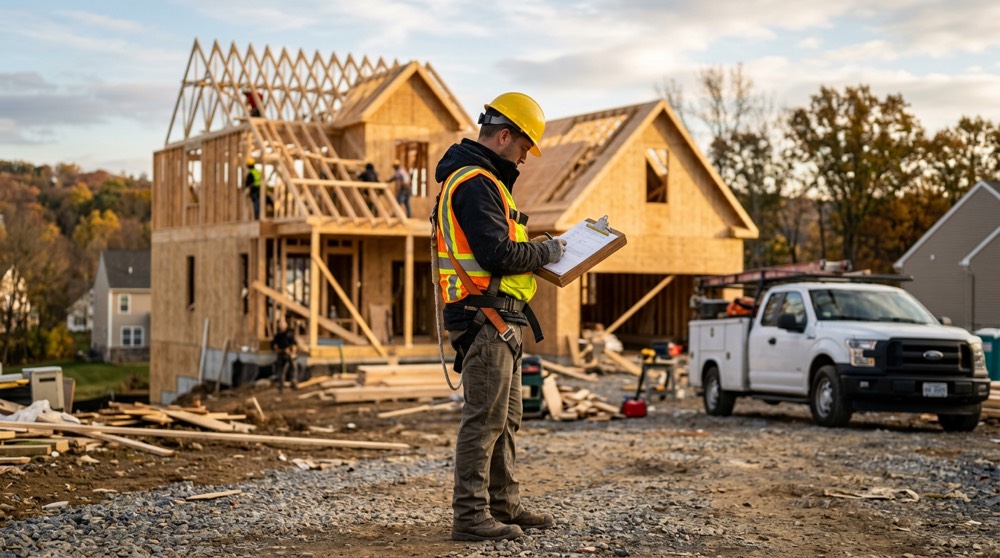
Contractor insurance is the package of business policies — general liability, workers' compensation, commercial auto, tools and equipment, builders risk, and surety bonds — that protects a Pennsylvania construction business from the lawsuits, injuries, property damage, and project losses it faces every day on the job. The right combination keeps a single claim from ending your company.

For a Berks County contractor, insurance is not a single product you buy once. It is a layered program that grows with your crew, your equipment, and the contracts you sign. This guide walks through every core coverage a Pennsylvania contractor should understand, what each one pays for, what it costs, and what the law actually requires — so you can build a program that matches your real exposure instead of guessing.

What is contractor insurance?

Contractor insurance is a combination of commercial policies bundled to cover the specific risks of construction work — third-party injuries, property damage, employee injuries, vehicle accidents, stolen tools, and unfinished-project losses. No single policy covers all of it; contractors assemble several coverages into one program.

Think of it as a stack. A general liability policy sits at the base, handling claims from customers and the public. Workers' compensation handles your employees. Commercial auto handles your trucks. Inland marine covers your tools and equipment. Builders risk protects the project itself while it is under construction. Surety bonds guarantee your performance to project owners and licensing bodies. Most contractors carry a Business Owner's Policy (BOP) that packages liability and property together, then add the other coverages as their work demands.

What makes construction different from most small businesses is how many parties have a financial stake in your coverage. A homeowner cares that you are insured. A general contractor requires it in writing. A project owner names themselves on your policy. A lender may demand builders risk before releasing funds. Your subcontractors' coverage rolls up into yours at audit. Because so many relationships hinge on your insurance, a contractor's program is as much a business-development tool as a safety net — the firms that carry clean, complete coverage simply win more work.

Why Pennsylvania contractors need coverage

Construction is one of the most hazardous industries in the country, and that risk translates directly into insurance claims. According to the U.S. Bureau of Labor Statistics, construction and extraction occupations recorded 1,032 fatal work injuries in 2024, out of 5,070 fatal work injuries nationwide — making construction one of the deadliest fields to work in. Every serious jobsite incident is a potential claim against a contractor's policies.

Beyond the human cost, contractors face a stack of financial exposures a homeowner or office business never sees: a ladder that falls on a client's car, a subcontractor injured on your site, a truck accident in a company vehicle, a theft of $40,000 in tools from a locked trailer overnight, or a half-built addition destroyed by fire before the owner ever takes possession. In Reading and across Berks County, a mid-size general contractor can carry six-figure equipment values and juggle several active jobsites at once — any one of which can generate a claim large enough to close an uninsured shop.

The core policies every contractor should carry

Most Pennsylvania contractors build their program from six core coverages. Not every contractor needs all six at full limits, but every contractor should understand each one and make a deliberate decision about it rather than discovering the gap after a loss.

The essentials are general liability, workers' compensation, commercial auto, tools and equipment (inland marine), builders risk, and surety bonds. A newer solo operator might start with general liability and a tools floater; a growing firm with employees, a fleet, and bonded public work needs the full stack. For a plain-language primer aimed at smaller shops, see our overview of construction insurance for small contractors.

General liability insurance

General liability (GL) insurance covers third-party bodily injury and property damage a contractor causes during the course of work — a customer who trips over your materials, a neighbor's fence your crew backs into, or water damage from a plumbing mistake. It is the single most requested coverage in construction because almost every contract and general contractor requires it.

GL also covers products-completed operations — damage that shows up after you finish a job — and the legal defense costs of a covered claim, which can rival the settlement itself. Most Pennsylvania contractors carry limits of $1 million per occurrence and $2 million aggregate, because that is the floor most GCs and project owners demand before they will let you on site. General liability is deep enough that it earns its own detailed treatment; the coverage components, exclusions, and typical costs are worth a full read.

Workers' compensation insurance

Workers' compensation pays for medical treatment and lost wages when an employee is injured on the job, and in Pennsylvania it is not optional. Coverage is mandatory for most employers under Pennsylvania law, and a contractor who fails to carry it can face employee lawsuits and criminal prosecution from the state.

For contractors, workers' comp carries an extra wrinkle: uninsured subcontractors. If you hire a 1099 sub who does not carry their own coverage, your policy can be charged for them at audit — and you can be held responsible if they are hurt on your site. That is why collecting a certificate of insurance from every sub is a core risk-management habit, not just paperwork. Workers' comp premiums are driven by your payroll and your class codes, so the way your crew is classified has a direct effect on cost.

Commercial auto, tools, and equipment

Personal auto policies exclude vehicles used primarily for business, which means a contractor's trucks and vans need commercial auto insurance. It covers liability for accidents your drivers cause, plus physical damage to the vehicles themselves, and it is the coverage most likely to produce a large, fast-moving claim — a work-truck collision can involve serious injuries and third-party property damage in a single incident.

Your tools and equipment need their own protection, too. A GL policy will not pay to replace stolen power tools or a damaged skid steer; that falls to inland marine coverage, often called a tools and equipment floater or contractors equipment policy. It follows your gear wherever it goes — jobsite, truck, storage yard — and covers theft, fire, and accidental damage. For a shop with a loaded trailer and heavy machinery, this coverage frequently pays for itself the first time a trailer is broken into.

Builders risk and surety bonds

Builders risk insurance protects a structure while it is under construction — covering fire, wind, theft, and vandalism to the building, materials, and equipment on site before the project is complete and handed over. On a new build or major renovation, the party responsible for builders risk is usually spelled out in the contract, and a gap here can leave hundreds of thousands of dollars of work-in-progress uninsured.

Surety bonds are a different animal: they are not insurance that protects you, but a three-party guarantee that protects the project owner or the public. License bonds, bid bonds, payment bonds, and performance bonds all promise that you will meet an obligation — hold your license responsibly, honor your bid, pay your subs, or finish the job. Public work in Pennsylvania and many private contracts require them, and understanding the difference between a bond and an insurance policy keeps contractors from assuming they are covered when they are only guaranteed.

How much does contractor insurance cost?

Contractor insurance cost depends on your trade, payroll, revenue, claims history, vehicles, and the coverage limits your contracts require — so a solo handyman and a 20-person mechanical contractor pay very different premiums. There is no flat rate; pricing is built from your specific exposure.

General liability for a small contractor commonly runs from a few hundred to a few thousand dollars a year depending on trade risk, while workers' compensation is priced per $100 of payroll and varies sharply by class code — a roofing crew costs far more to insure than a finish carpenter. Commercial auto, equipment floaters, and bonds each add their own line. The most reliable way to control cost is to right-size your limits to what your contracts actually require, keep a clean loss history, and classify your payroll accurately so you are not overcharged at audit. An independent agent can compare several carriers on the same submission rather than quoting a single company.

It also helps to understand what moves your premium up or down year to year. Adding a new trade or service — say, a remodeler who starts doing roofing — changes your risk classification and can reset your rate. A claim, even a small one, can follow you for three years through your experience modifier. Growing revenue and payroll raise premium simply because there is more exposure to insure. On the other side, a documented safety program, drug-free-workplace policies, and higher deductibles can all lower cost. Because the levers are specific to your operation, the annual renewal is worth a real conversation with your agent rather than an automatic re-sign.

What coverage do Pennsylvania contractors legally need?

Pennsylvania law requires workers' compensation for nearly every employer, and commercial auto liability for business vehicles — those two are legal mandates. General liability and bonds are usually required by contract or licensing rather than by state statute, but in practice you cannot win most work without them.

Pennsylvania's Home Improvement Consumer Protection Act requires most residential contractors to register with the state Attorney General and to carry at least $50,000 in liability coverage to register. Municipalities and project owners layer their own requirements on top — many Berks County jobs demand $1 million GL limits, additional-insured status, and a waiver of subrogation before you can start. The practical answer is that "required" coverage is a blend of state law, licensing rules, and contract terms, and the contracts almost always set the highest bar.

Certificates of insurance: proving you are covered

A certificate of insurance (COI) is the one-page document that proves your coverage to general contractors, project owners, and licensing bodies — and on most jobs, no COI means no start. It summarizes your policies, limits, and effective dates, and it is requested on virtually every commercial and many residential projects.

Contractors trip over COIs constantly: an expired certificate, a missing additional-insured endorsement, or the wrong entity named can stall a job or blow up a contract. Because the COI ties your entire program together in the eyes of the people who hire you, it is worth understanding exactly how it works and what the endorsements on it mean — our guide to what contractors need to know about certificates of insurance breaks it down.

Common coverage gaps contractors miss

The most damaging contractor insurance losses usually come from gaps — risks a contractor assumed were covered but were not. The frequent offenders are uninsured subcontractors, missing additional-insured endorsements, lapsed certificates, tools excluded from a general liability policy, and no builders risk on a ground-up job.

Each gap has a simple cause. Contractors assume a subcontractor's insurance protects them, when in reality an uninsured sub becomes their exposure at audit. They assume general liability covers their tools, when theft of equipment actually falls to inland marine. They assume "I have insurance" satisfies a contract, when the contract specifically required additional-insured status and a waiver of subrogation the base policy never included. They let a certificate expire mid-project and stall the job. And they take on new construction without confirming who carries builders risk, leaving the work-in-progress uninsured. None of these gaps is exotic; they are the everyday holes an experienced agent checks for before they turn into a denied claim. Reviewing your program against the actual language of your contracts — not just the fact that you "have coverage" — is the single most valuable habit a growing contractor can build.

Choosing coverage for your Berks County business

The right contractor insurance program matches your actual exposure — your trade, crew size, equipment values, vehicles, and the contracts you sign — rather than a one-size template. The goal is to close the gaps that would sink you while not overpaying for limits your work does not demand.

Start with the coverages the law and your contracts require, then layer in the protection that fits your operation: a tools floater if you carry expensive gear, builders risk when you take on ground-up work, and an umbrella policy once your contracts start asking for higher limits. Because construction pricing and requirements shift constantly, contractors benefit from working with an independent agent who knows the Pennsylvania market and can compare carriers on your behalf. A local Reading-based agency that writes construction risk every day can spot the endorsement gaps a general online quote will miss.

Frequently Asked Questions

Do independent contractors need insurance if they have no employees?

Yes. Even a solo contractor with no employees needs general liability insurance, because third-party injury and property-damage claims do not depend on having a crew. Most clients and general contractors also require a certificate of insurance before they will hire you, and a tools floater protects the equipment you depend on to work.

Is a contractor bond the same as contractor insurance?

No. Insurance protects you and pays your claims, while a surety bond is a three-party guarantee that protects the project owner or public if you fail to meet an obligation. If a bond pays out, the surety recovers that money from you. Contractors need both: insurance for losses, and bonds for licensing and contract guarantees.

How much liability insurance do Pennsylvania contractors need?

Most Pennsylvania contracts and general contractors require at least $1 million per occurrence and $2 million aggregate in general liability. Pennsylvania's Home Improvement Consumer Protection Act sets a $50,000 minimum to register as a residential contractor, but that floor is far below what real jobs demand, so contract requirements usually drive the number.

Does contractor insurance cover subcontractors?

Not automatically. Subcontractors need their own general liability and workers' compensation, and you should collect a certificate of insurance from each one. Uninsured subs can be charged to your workers' comp policy at audit and can expose you to liability if they are injured on your site, so verifying sub coverage is a core risk-management step.

What is the difference between general liability and workers' compensation?

General liability covers injuries and property damage to third parties — customers, the public, and their property. Workers' compensation covers your own employees when they are hurt on the job, paying their medical bills and lost wages. They protect different groups of people, both are commonly required, and together they form the backbone of a contractor's program.

Protect your construction business

A single uncovered claim can undo years of work. American Insuring Group builds contractor insurance programs tailored to Pennsylvania construction firms — comparing multiple carriers to match your coverage to your real exposure and your contract requirements.

Contact American Insuring Group online in Reading, PA for a no-obligation review of your contractor insurance program, or call us at (610) 775-3848.
Tags: Construction Insurance, Contractor Insurance

Motor Truck Cargo Insurance: What It Covers

Posted by David Ross on Thu, Oct 08, 2026

Call us for motor truck cargo insurance in Philadelphia, Pittsburgh, Erie, Lancaster, Lebanon, Allentown, Reading, and anywhere in PA

Motor truck cargo insurance covers the freight a trucking company is hauling against loss or damage while it is in transit — from causes like collision, fire, theft, and certain acts of nature. It protects the value of the goods, not the truck itself, and it is what allows a carrier to meet its legal responsibility to the shippers whose loads it carries. For any operation moving freight for hire, it is essential coverage.

A trucking company can carry excellent liability and physical-damage coverage on its vehicles and still be financially exposed to the value of what is in the trailer. When a load is destroyed in an accident, stolen at a truck stop, or damaged by fire, the carrier is often on the hook to the shipper — and motor truck cargo insurance is the coverage that responds. That exposure is growing: Verisk CargoNet recorded 3,625 cargo theft events in 2024, a 27% jump over 2023, with an average value of $202,364 per theft. Building cargo protection into a strong commercial truck insurance [https://www.aigltd.com/pa-truck-insurance] program is how carriers keep a single bad load from becoming a business-threatening loss.

What Does Motor Truck Cargo Insurance Cover?

Motor truck cargo insurance covers physical loss or damage to the freight a carrier is transporting, up to the policy limit, for covered causes such as collision, overturn, fire, theft, and striking of a load. It typically also includes related costs like debris removal and, for refrigerated freight, losses from a covered breakdown of the cooling system.

The coverage is tied to the goods in transit, which distinguishes it from the policies protecting the vehicle. Most cargo policies specify a per-vehicle limit that should be set high enough to cover the maximum value a carrier ever hauls at one time. Many forms also extend to the carrier's legal liability for the freight while it is temporarily held at a terminal or dock in the ordinary course of transit, though the exact scope of that "in transit" definition varies and is worth confirming. Policies also carry important exclusions and conditions — common examples include certain high-value commodities (electronics, alcohol, tobacco, pharmaceuticals), unattended-vehicle theft restrictions, and requirements to properly secure the load. Because carriers haul different commodities under different conditions, cargo forms vary significantly, and reading the covered-perils and exclusions sections closely is critical. Coverage terms differ by insurer and policy, so limits and conditions should be matched to the actual freight being moved.

Is Cargo Insurance Required by Law?

Cargo insurance is legally required for some motor carriers and contractually required for many more. Under federal rules, motor carriers transporting household goods must maintain cargo insurance filed with the Federal Motor Carrier Safety Administration — historically at minimum limits of $5,000 per vehicle and $10,000 per occurrence — while general-freight carriers are usually not federally mandated to carry it.

In practice, though, the market requires far more than the federal floor. Shippers, brokers, and freight contracts routinely require carriers to carry cargo coverage — often $100,000 or more per load — before they will tender freight. A Reading-area fleet running loads down the I-78 and I-81 corridors will find that most broker load agreements specify a minimum cargo limit as a condition of doing business. So while a general-freight carrier may not face a legal mandate, it will rarely get freight without adequate cargo coverage. Requirements vary by commodity, route, and contract, and household-goods movers face specific FMCSA filing rules, so carriers should confirm both their legal and contractual obligations.

How Much Motor Truck Cargo Coverage Do You Need?

The right cargo limit is driven by the maximum value of freight you haul at any one time, not the average. If a single trailer can carry $150,000 in goods, a $50,000 cargo limit leaves you personally exposed for the difference on a total loss.

Setting the limit correctly starts with an honest look at your highest-value loads and the commodities you handle. Carriers hauling expensive or theft-prone freight need higher limits and should confirm the policy does not exclude their specific cargo. It is also worth confirming how the policy values a loss — actual cash value versus the invoice or "sales" value of the goods — because the two can differ substantially on a total loss and change how much a claim actually pays. It is equally important to review deductibles, unattended-vehicle theft provisions, and any commodity restrictions that could void a claim. Many carriers coordinate cargo coverage with the rest of their fleet program — including commercial vehicle insurance on the trucks themselves — so limits and terms line up across the operation.

Carriers who run loads across borders should also confirm how coverage responds internationally; our overview of insurance for international trucking explains why domestic cargo coverage often stops at the border. Because needs vary widely by operation, an independent broker can help right-size limits without overpaying.

Frequently Asked Questions

What is the difference between motor truck cargo insurance and physical damage coverage? Motor truck cargo insurance covers the freight being hauled, while physical damage coverage (comprehensive and collision) covers the truck and trailer. They protect two different things that are often damaged in the same event. A carrier generally needs both: cargo insurance to satisfy its responsibility to shippers for the load, and physical damage coverage to repair or replace its own equipment.

Does cargo insurance cover theft from an unattended truck? It can, but many cargo policies restrict or exclude theft when the vehicle is left unattended and unsecured, especially for high-value commodities. Some require the truck to be locked, parked in a secured lot, or equipped with specific anti-theft measures for coverage to apply. Because cargo theft has surged in recent years, these conditions are enforced closely — read your policy's theft provisions carefully and follow them.

What types of cargo are commonly excluded or limited? Cargo policies frequently limit or exclude high-value and high-theft commodities such as electronics, alcohol, tobacco, pharmaceuticals, jewelry, and money, as well as certain hazardous materials and live animals. If your operation hauls any of these, you need a policy specifically written to cover them, often with higher premiums and stricter security requirements. Never assume a standard cargo form covers specialty freight without confirming it in writing.

How does cargo insurance handle refrigerated (reefer) loads? Many cargo policies offer reefer breakdown coverage for spoilage caused by a mechanical failure of the refrigeration unit, but it is often an add-on with its own conditions. Insurers typically require documented maintenance of the reefer unit and may exclude losses from driver error or a unit that was improperly set. Carriers hauling temperature-sensitive freight should confirm reefer coverage is included and understand its requirements.

Let Us Help You Protect Every Load

Do you have questions about motor truck cargo insurance or coverage for your fleet? Contact American Insuring Group for competitive rates on cargo and commercial trucking coverage built around the freight you actually haul. As independent brokers, we shop the market to match your operation with the right limits and terms.

Call American Insuring Group today at (610) 775-3848 or contact American Insuring Group [https://www.aigltd.com/contact] online. Coverage specifics vary by policy, commodity, and state — let us help you protect every mile and every load.

Tags: Commercial Vehicle Insurance, Cargo Trucking Insurance

Landlord Insurance for Vacant and Between-Tenant Rentals

Posted by David Ross on Sat, Oct 03, 2026

Call AIG for best landlord insurance in Philadelphia, Pittsburgh, Reading, Harrisburg, Erie, Allentown, York, and throughout Pennsylvania

A standard landlord insurance policy often reduces or suspends coverage once a rental property sits empty for a set number of consecutive days — commonly 30 or 60. To stay protected while a unit is vacant or between tenants, most landlords need a vacancy permit endorsement or a separate vacant property policy. Leaving that gap unaddressed is one of the most common and costly mistakes rental property owners make.

An empty rental feels lower-risk than an occupied one, but insurers see it the opposite way. Vacant buildings are more exposed to vandalism, theft, undetected water damage, and delayed discovery of problems because no one is there to notice a leak, a break-in, or a failing furnace. That is why the vacancy clause buried in most landlord policies can quietly leave an owner uninsured at the worst possible moment. With the U.S. rental vacancy rate at 7.3% in the first quarter of 2026, per U.S. Census Bureau data reported by the Federal Reserve, vacancy is a normal part of owning rentals — which makes understanding how your landlord insurance [https://www.aigltd.com/landlord-insurance] treats it essential.

Does Landlord Insurance Cover a Vacant Property?

A standard landlord policy generally does cover short, expected gaps between tenants, but coverage typically changes once a property has been vacant beyond the policy's stated vacancy period. After that point, many policies limit or exclude key perils — most notably vandalism, glass breakage, water damage, and theft.

This is the trap that catches many owners. The property is still insured "on paper," but the specific losses most likely to happen to an empty building are exactly the ones the vacancy clause carves out. A pipe bursts in a unit that has been empty for 45 days, and the claim is denied because the policy suspended water-damage coverage after 30 days of vacancy. Liability can shift as well: some policies also narrow the coverage that would respond if a trespasser or contractor is injured on a property left standing empty. The lesson is to read the vacancy provision in your own policy before a unit goes empty, not after a loss. Vacancy definitions and time limits vary widely between insurers and policy forms, so never assume yours matches a competitor's or a prior policy's terms.

How Long Can a Rental Sit Vacant Before Coverage Changes?

Most landlord and dwelling policies define a vacancy trigger of 30 or 60 consecutive days, after which certain coverages are reduced or suspended. The exact number, and which perils are affected, is written into your specific policy — there is no universal standard.

Because that window is shorter than many owners expect, a routine turnover can cross the line without anyone realizing it. Consider a Berks County landlord renovating a Reading duplex between tenants: if the work stretches past the policy's 30- or 60-day threshold, the property may quietly lose vandalism and water-damage protection right when the building is most exposed. The fix is usually straightforward — a vacancy permit endorsement extends coverage through a known vacancy, and a dedicated vacant property policy covers longer or repeated vacancies. Both are far cheaper than an uncovered loss. If you know a unit will be empty for an extended period, notify your broker before the vacancy begins so coverage can be arranged in advance.

What Is Vacant Property Insurance?

Vacant property insurance is a specialized policy designed to cover a building that is unoccupied and, in many cases, unfurnished — filling the exact gap a standard landlord policy leaves open during extended vacancies. It restores protection for perils like fire, vandalism, liability, and often water damage that the vacancy clause would otherwise limit.

These policies are built for real-world situations: a rental undergoing major renovation, a property waiting to be sold or leased, an inherited home sitting empty, or a unit between long-term tenants. Coverage can typically be written for a set term — three, six, or twelve months — and adjusted or canceled as the property's status changes, so an owner is not locked into a full-year policy for a two-month gap. Liability protection matters here too — an empty property still attracts trespassers and creates injury exposure, and vacant property policies can respond to those claims.

Disclosure is part of the equation as well: if a property is vacant and the insurer is not told, a later claim can be denied on the grounds that the vacancy was misrepresented, even under an otherwise valid policy. Being upfront about a unit's occupancy status is what keeps the coverage enforceable when you need it. Owners with multiple properties sometimes coordinate vacant coverage alongside their broader portfolio, including any commercial property insurance on larger buildings. Because forms and endorsements differ by insurer, an independent broker can help match the right solution to how long and why the property will be vacant.

Frequently Asked Questions

Why is a vacant rental considered higher risk? Empty buildings carry more risk because problems go unnoticed and unaddressed. There is no tenant to report a small roof leak before it becomes major water damage, to deter break-ins, or to notice a heating failure that leads to frozen pipes. Vacant properties also attract vandalism and squatters. Insurers price and restrict coverage accordingly, which is why the vacancy clause exists in standard landlord policies in the first place.

Does a vacancy clause apply if the unit is furnished but empty? It can, because most vacancy provisions turn on occupancy, not furnishings. A unit with furniture still in it may be considered "unoccupied" if no one is living there, and some policies distinguish between "vacant" and "unoccupied" with different rules for each. The definitions are policy-specific and easy to misread, so confirm exactly how your policy defines the terms before relying on continued coverage.

How do I keep coverage during a renovation between tenants? Tell your insurance broker before the renovation starts. Depending on the scope and timeline, the right tool may be a vacancy permit endorsement on your existing landlord policy, a builder's risk policy for the construction work, or a vacant property policy for a longer gap. Arranging this in advance avoids the coverage suspension that can otherwise take effect once the unit passes the policy's vacancy threshold.

Is vacant property insurance more expensive than standard landlord insurance? Vacant property coverage often costs more than a standard landlord policy because the underlying risk is higher, but the difference is minor compared with an uninsured loss on an empty building. Pricing depends on the property's condition, location, length of expected vacancy, and coverage limits. An independent broker can compare markets to find competitive terms for the specific vacancy situation you are facing.

Protect Your Rental Between Tenants with the Right Coverage

Are you facing a vacancy, a renovation, or a gap between tenants? Contact American Insuring Group to make sure your rental stays protected when it matters most. As independent brokers, we shop the market to find competitively priced landlord and vacant property coverage matched to your situation.

Call American Insuring Group today at (610) 775-3848 or contact American Insuring Group online. Coverage terms vary by policy and state — let us help you close the gap before it costs you.

Tags: Landlord Insurance, Commercial Insurance, commercial property insurance

How the Workers' Comp Experience Mod Affects Your Premiums

Posted by David Ross on Mon, Sep 28, 2026

aig-workers-comp-experience-mod-berks-county

Your workers' compensation experience modification factor — often called the "experience mod" or EMR — is a number that compares your business's actual claims history to what would be expected for similar businesses of your size. It directly multiplies your premium: a mod above 1.00 raises your cost, while a mod below 1.00 lowers it. Controlling that number is one of the most powerful ways to control workers' comp spending over time.

Two companies in the same industry, paying the same base rates, can pay very different workers' compensation premiums — and the experience mod is usually why. The mod rewards employers with better-than-average loss records and penalizes those with worse ones, so it functions as both a pricing tool and a financial incentive to run a safer operation. With private-industry employers reporting 2.5 million nonfatal workplace injuries and illnesses in 2024, according to the U.S. Bureau of Labor Statistics, the difference between a good mod and a bad one adds up to real money. Understanding how the factor works is the first step toward managing your workers' compensation insurance costs.

What Is a Workers' Comp Experience Mod?

A workers' comp experience mod is a numerical factor, centered on 1.00, that adjusts your premium up or down based on your company's past claims relative to expected losses for businesses like yours. A mod of 1.00 means your losses are exactly average; below 1.00 means better than average; above 1.00 means worse.

Think of the mod as a report card on your loss history. It is calculated by a rating bureau using several years of your payroll and claims data, then applied as a multiplier to your manual premium. If your manual premium is $50,000 and your mod is 0.90, you pay $45,000; if your mod is 1.20, you pay $60,000 for the exact same coverage. That swing is why larger employers watch the number so closely. Typically, only businesses whose premiums exceed a minimum threshold are large enough to qualify for experience rating at all — smaller employers are pooled at the base rate until they reach that size.

How Is the Experience Modification Factor Calculated?

The experience modification factor is calculated by comparing your business's actual losses over a defined experience period — usually three years, excluding the most recent policy year — against the expected losses for a business of your type and payroll. Rating bureaus weigh the frequency of claims more heavily than the severity of any single claim.

That frequency-over-severity design is important to understand. A pattern of many small claims signals an ongoing safety problem and tends to push a mod higher than one large, unexpected claim of the same total dollar value. In Pennsylvania, experience rating is administered by the Pennsylvania Compensation Rating Bureau (PCRB) rather than the National Council on Compensation Insurance used in most states — one reason PA employers should work with a broker familiar with the state's specific rating rules. The calculation also splits losses into "primary" (the portion of each claim that counts most heavily) and "excess" components, which is why keeping individual claims small has an outsized effect on your final number. Exact formulas and thresholds vary by state and rating bureau.

How Can a Business Lower Its Experience Mod?

A business lowers its experience mod by reducing both the number and cost of claims over time — the mod responds to sustained improvement, not one-time fixes. The most effective levers are preventing injuries in the first place, managing claims aggressively when they do happen, and ensuring the data feeding your mod is accurate.

The mod also matters beyond the premium itself. Many general contractors, facility owners, and public agencies set a maximum experience mod — often 1.00 — as a condition of bidding or being hired, so a high mod can quietly cost a company work, not just money. That makes controlling it a competitive issue as much as an insurance one.

Practical steps include building a documented safety program, training employees consistently, and investigating every incident to eliminate root causes. Equally important is a return-to-work program that brings injured employees back in modified-duty roles as soon as it is medically appropriate — this reduces the "primary" claim costs that drive the mod most. A light-duty assignment that keeps an employee productive during recovery often costs far less, in mod terms, than the same worker sitting fully out on wage-replacement benefits.

Employers should also audit their loss runs and payroll classifications regularly, because errors in reported claims or misclassified job codes can inflate a mod unfairly. Finally, prompt claim reporting and coordinated medical care help control the ultimate cost of each claim. Because a mod reflects several years of history, the businesses that win the long game treat these practices as continuous discipline. Pairing a strong safety culture with the right coverage — and, where relevant, coordinated business liability insurance — protects both your people and your premiums.

Frequently Asked Questions

What is a good workers' comp experience mod? Any experience mod below 1.00 is generally considered good, because it means your business has better-than-average losses and pays a credit on its premium. A mod of exactly 1.00 is average. Consistently strong safety performance can push a mod meaningfully below 1.00 over several years, producing significant savings. What counts as "good" for your specific operation depends on your industry's expected losses.

How many years of claims affect my experience mod? Most experience mods use a three-year window, and importantly, it excludes your most recent completed policy year to allow claims time to develop. That means a bad year continues to affect your mod for roughly three years after it ends — and a good year does the same. Because the effect is multi-year, improving your loss record pays off gradually rather than instantly. Specific periods vary by rating bureau.

Does a single large claim ruin my experience mod? Not as much as many owners fear. Experience rating formulas are built to weigh claim frequency more heavily than the severity of one large, unexpected loss, and they cap how much any single claim can affect the primary portion of your calculation. A pattern of frequent small claims typically damages a mod more than one serious injury. Still, prompt claim management helps limit the impact of any loss.

Who calculates the experience mod in Pennsylvania? In Pennsylvania, the Pennsylvania Compensation Rating Bureau (PCRB) calculates and administers experience modification factors, unlike most states that rely on the National Council on Compensation Insurance. This is why PA employers benefit from working with brokers and insurers who understand PCRB's rules and filings. If you operate in multiple states, more than one rating bureau may be involved, each with its own methodology.

Let Us Help You Manage Your Workers' Comp Costs

Do you have questions about your experience mod or workers' compensation premiums? Contact American Insuring Group for competitive rates and the loss-control resources that help bring your mod down over time. As independent brokers, we shop the market to find the right policy and help you build the safety and claims practices that lower long-term costs.

Call American Insuring Group today at (610) 775-3848 or contact American Insuring Group online. Specifics vary by policy and state — let us help you get it right.

Tags: Workers Compensation Insurance, workers comp costs

Liquor Liability Insurance for Restaurants and Bars

Posted by David Ross on Wed, Sep 23, 2026

Call us for liquor liability insurance in Philadelphia, Pittsburgh, Erie, Lancaster, Lebanon, Allentown, Reading, and throughout PA

Liquor liability insurance protects a restaurant, bar, or tavern from claims that arise when a customer it served alcohol goes on to injure someone or damage property. If your establishment sells, serves, or furnishes alcohol, this coverage responds to lawsuits, legal defense costs, and settlements that a standard general liability policy typically excludes — making it essential protection for any business with a liquor license.

Serving alcohol is central to the business model of most restaurants and bars, but it also creates a distinct legal exposure that ordinary business coverage was never designed to absorb. When a patron is over-served and later causes a car accident, a fight, or another injury, the injured party can pursue the establishment that provided the alcohol — not just the individual. Liquor liability insurance exists to answer that specific risk. For an industry the National Restaurant Association projected would reach a record $1.1 trillion in U.S. sales in 2024 [https://restaurant.org/research-and-media/media/press-releases/restaurant-industry-sales-forecast-to-set-1-1-trillion-record-in-2024/], the stakes of getting alcohol coverage right are substantial. A well-structured restaurant insurance program  treats liquor liability as a core component, not an afterthought.

What Does Liquor Liability Insurance Cover?

Liquor liability insurance covers bodily injury and property damage claims brought against your business because of the way it sold, served, or furnished alcohol. It typically pays for legal defense, court costs, settlements, and judgments up to the policy limits, whether or not your establishment is ultimately found at fault.

The coverage usually responds to a range of alcohol-related incidents. These include injuries caused by an intoxicated patron after leaving the premises — most commonly a drunk-driving accident — as well as assaults, fights, and property damage connected to over-service. Some policies also address claims tied to serving a minor. Because these exposures often generate the largest and most emotionally charged lawsuits a hospitality business will ever face, liquor liability limits are frequently written to match or exceed the establishment's general liability limits. Coverage terms, exclusions, and available limits vary by insurer, policy, and state, so the specific language matters as much as the limit.

Why Doesn't General Liability Cover Alcohol Claims?

Most commercial general liability policies contain a liquor liability exclusion that removes coverage for any business "in the business of" manufacturing, selling, serving, or furnishing alcohol. That exclusion is precisely why restaurants and bars need a separate liquor liability policy or endorsement to fill the gap.

The distinction trips up many owners. A restaurant may carry solid commercial general liability coverage for slip-and-fall injuries or a customer hurt by falling equipment, yet still have zero protection for an alcohol-related claim. General liability handles the everyday premises risks; liquor liability handles the risk created by the act of serving alcohol itself. A business that holds a liquor license and assumes its general policy "covers everything" is often one incident away from an uninsured six-figure lawsuit. The two coverages are designed to work together, and reputable carriers underwrite them accordingly.

Who Needs Liquor Liability Insurance in Pennsylvania?

Any Pennsylvania business that serves or sells alcohol needs liquor liability insurance — restaurants, bars, nightclubs, cafes, breweries, caterers, and even food trucks with a liquor license. The exposure follows the alcohol, not the size of the operation, so a small neighborhood tavern faces the same category of risk as a large venue.

Pennsylvania makes this coverage especially important through its dram shop provisions in the state Liquor Code. Under Pennsylvania law, an establishment can be held liable when it serves alcohol to a "visibly intoxicated" person who then causes harm to a third party. That means a Reading or Berks County bar that keeps serving a patron who is clearly impaired can be pulled into a lawsuit brought by someone that patron later injures — even miles away and hours later. Many landlords, franchisors, and special-event venues also require proof of liquor liability coverage before they will do business with you. Because dram shop standards and liability rules vary from state to state, Pennsylvania establishments should confirm their coverage is built for the specific requirements they operate under.

How Much Does Liquor Liability Insurance Cost?

Liquor liability premiums depend on factors specific to each establishment, so there is no single price. Insurers weigh the share of revenue that comes from alcohol, total sales, hours of operation, whether entertainment or late-night service is involved, the venue's claims history, and staff training practices such as certified responsible-serving programs.

An establishment that generates most of its revenue from food and serves beer and wine at dinner presents a very different risk than a late-night nightclub built around high-volume liquor sales, and premiums reflect that gap. Owners can often improve their pricing by documenting server-training certifications, maintaining clear over-service policies, and combining liquor liability with their other business coverages — such as property, general liability, and, where applicable, commercial property insurance — into a coordinated program. Because rates and available credits vary widely between carriers, working with an independent broker who can shop multiple markets is usually the most reliable path to competitive pricing. Never assume a quoted premium reflects the best available terms without a market comparison.

Frequently Asked Questions

Is liquor liability insurance required by law in Pennsylvania? Pennsylvania does not universally mandate liquor liability insurance for every license holder, but the state's dram shop provisions create real liability for serving visibly intoxicated patrons. In practice, many landlords, lenders, and event contracts require proof of the coverage, and operating without it leaves an establishment exposed to alcohol-related lawsuits that other policies exclude. Requirements can change, so verify current rules for your license type.

Does liquor liability cover fights or assaults on the premises? Many liquor liability policies respond to bodily injury from fights or assaults when the incident is connected to the service of alcohol, but coverage varies significantly by policy. Some carriers include assault-and-battery coverage automatically, others offer it by endorsement, and some exclude it. Because this is a common and costly exposure for bars and nightclubs, confirm exactly how your policy treats assault and battery.

What is the difference between liquor liability and dram shop coverage? The terms are closely related and often used interchangeably. "Dram shop" refers to the legal doctrine that holds an alcohol-serving business responsible for harm caused by an intoxicated patron. Liquor liability insurance is the coverage that responds to those dram shop claims. In short, dram shop law creates the exposure, and liquor liability insurance is how a restaurant or bar protects itself against it.

Do food trucks and caterers need liquor liability insurance? Yes, if they serve or furnish alcohol. A food truck or catering operation with a liquor license or a special-event permit carries the same fundamental exposure as a brick-and-mortar bar. Event venues and clients frequently require caterers to show liquor liability coverage before an event. The right limits depend on the scale and setting of the service, which a broker can help you assess.

Protect Your Establishment with the Right Liquor Liability Coverage

Do you have questions about liquor liability or restaurant insurance? Contact American Insuring Group for great rates on coverage built for restaurants, bars, taverns, and other hospitality businesses. As independent brokers, we shop the market to match your establishment with the right protection at the right price.

Call American Insuring Group today at (610) 775-3848 or contact American Insuring Group online. Coverage specifics vary by policy and state — let us help you confirm you are properly protected.

Tags: Restaurant Insurance, Liquor Liability Insurance

Preventing Worker's Compensation Claims

Posted by David Ross on Sat, Jul 25, 2026

2606-4-Preventing-Workers-Compensation-Claims1000

Every worker's compensation claim represents two things at once: a workplace injury that affected an employee, and a cost that flows through to the employer's experience modification factor and ultimately the premium. The good news is that the most effective way to lower worker's compensation costs is also the most ethically straightforward — prevent the injuries in the first place. Companies with strong safety cultures, well-trained employees, and disciplined risk-management practices consistently see fewer claims, lower experience mods, and meaningful savings on premiums year after year. The right workers' compensation insurance program covers what happens when something goes wrong; the right safety program keeps things from going wrong in the first place.

Workplace Safety Initiatives That Actually Reduce Claims

Effective workplace safety is built on systems, not slogans. Companies that consistently produce low claim rates tend to share several characteristics: documented safety policies that address the actual hazards in their operations; visible leadership commitment to safety, including from senior management; clear reporting procedures for incidents, near-misses, and unsafe conditions; and a willingness to investigate every claim thoroughly to identify root causes that can be eliminated.

Practical safety initiatives vary by industry but commonly include personal protective equipment programs, machine guarding and lockout/tagout procedures, ergonomic assessments for repetitive-motion exposures, slip-and-fall prevention, and clear protocols for handling hazardous materials. For office and service-based environments, workstation ergonomics and driver safety often dominate the claim picture. The common thread across all of these initiatives is documentation. Programs that are written down, reviewed regularly, and demonstrably enforced produce measurable claim reductions. Programs that exist only in informal practice do not.

Employee Training — The Multiplier on Every Other Effort

Even the best-designed safety program produces no results if employees do not know how to follow it. Training is what turns a written policy into actual safe behavior on the floor, in the field, or on the road. Effective training programs are not one-time onboarding events — they are ongoing systems that include initial training for every new hire, regular refresher training, specialized training when employees take on new tasks or equipment, and prompt retraining after any incident.

Industry-specific certifications, OSHA training where applicable, and documented training records also serve a second purpose: they create a record that the employer took reasonable steps to train its workforce on the relevant hazards. This documentation matters in claim handling and in the rare case where a claim is contested. From the insurance side, carriers consistently reward companies that demonstrate a real training program with better terms and rates. From the practical side, well-trained employees simply have fewer accidents. Either way, the return on training investment is one of the most reliable in workplace safety.

Regular Risk Assessments — Finding the Next Claim Before It Happens

Risk assessments are how a safety program stays current as the workplace changes. New equipment, new processes, new building layouts, new hires, and even seasonal shifts in workload all change the hazard profile of the operation. A risk assessment program that periodically reviews the actual conditions on the ground — and updates safety protocols accordingly — catches emerging exposures before they produce injuries.

Effective risk assessments combine several inputs: physical walk-throughs by qualified safety personnel, review of incident and near-miss reports, employee feedback about hazards they observe, and analysis of claim patterns to identify categories of injury that are repeating. Many insurance carriers offer loss control services as part of a workers' compensation policy, and these services can be a valuable second set of eyes on the operation. The companies that consistently win the long game on worker's compensation costs treat risk assessment as an ongoing discipline, not a once-a-year compliance exercise. Over time, that discipline shows up in the experience modification factor and, ultimately, in the renewal premium.

Let Us Help You Save on Worker's Compensation Insurance

Do you have questions about worker's compensation coverage or claim prevention? Contact American Insuring Group for the best rates on workers' compensation insurance. As independent brokers, we shop the market to find you the right policy and the loss control resources that keep your premiums moving in the right direction.

Call us today at (610) 775-3848 or contact us online to start saving.

Tags: Workers Compensation Insurance, workplace safety, worker's compensation, claim prevention

Insurance Coverage for International Trucking

Posted by David Ross on Sat, Jul 18, 2026

Contact us for Insurance Coverage for International Trucking. Serving Philadelphia, Pittsburgh, Erie, Lancaster, Allentown, Reading, York, Mechanicsburg, and everywhere in PA.

Trucking operations that cross national borders face a layer of complexity that domestic-only fleets never have to manage. Coverage requirements differ from country to country. Standard domestic policies often stop providing coverage the moment a truck leaves the United States. Foreign jurisdictions have their own insurance regulations, their own claim procedures, and their own court systems for handling disputes. For trucking companies that operate internationally — whether routinely or occasionally — building the right insurance program is essential to keeping freight moving and protecting the business from exposures that domestic coverage simply will not address. The right commercial trucking insurance program accounts for every mile, including the ones across a border.

Requirements for Cross-Border Trucking

The first thing every international trucking operation needs to understand is that the foreign country sets its own minimum insurance requirements for commercial vehicles operating on its roads. Canada and Mexico, the two most common destinations for US-based trucking companies, each have their own rules. Canadian provinces require proof of liability coverage that meets or exceeds Canadian minimums, and many require additional endorsements or filings specific to operating in that province. Mexico requires Mexican liability coverage from a Mexican-licensed insurer — US auto liability policies generally do not satisfy Mexican law, no matter how high the limits.

Beyond the country-specific requirements, US-based carriers operating internationally must also maintain federal compliance with FMCSA requirements, cargo insurance appropriate to the freight being hauled, and any client-required coverages specified in shipping contracts. Documentation is critical. Carriers should be prepared to produce proof of insurance — in formats acceptable to foreign authorities — at any border crossing or roadside stop. Failing to meet documentation requirements can result in detained loads, fines, or refused entry, any of which can disrupt schedules and damage customer relationships.

Coverage for International Incidents

When an incident occurs outside US borders, the question of whether coverage responds — and how — depends entirely on the policy structure that was in place before the trip began. A domestic-only policy will typically exclude coverage for accidents, theft, or cargo loss occurring outside the United States. Carriers operating internationally need to confirm that their auto liability, physical damage, cargo, and general liability coverages all extend to the countries where their trucks operate — or that they have additional policies in place that do.

Mexican operations almost always require a separately purchased Mexican policy from a licensed Mexican insurer, written in Spanish and complying with Mexican regulations. Canadian operations are often handled through endorsements or broadenings on the US policy, though this varies by carrier and province. Coverage scope, deductibles, and claim-handling procedures may all differ from what the carrier expects under their US coverage. Understanding these differences before an incident happens is critical. Discovering them in the middle of a claim almost always means uncovered losses or significant out-of-pocket expense.

Dealing with Foreign Insurance Claims

Claims handling for international trucking incidents is significantly different from domestic claims and often more time-consuming. Foreign authorities may require the driver to remain at the scene for hours, or in serious cases, days. Police reports, accident documentation, and witness statements may need to be obtained in the local language. Damage assessments, repairs, and medical treatment may need to be coordinated through providers in the foreign country. Legal proceedings, if they arise, take place under foreign law and in foreign courts.

Carriers operating internationally benefit greatly from working with insurance programs that include international claims-handling capability. This may mean a carrier with established offices and adjusters in the destination country, third-party administrators with cross-border experience, or simply a US broker who has handled enough international claims to coordinate the process effectively. The carrier and driver should know — before any trip — exactly who to call when something happens, what documentation to gather, and how to communicate with foreign authorities. Preparation cannot prevent every incident, but it can dramatically reduce the chaos and the cost when one does occur.

Let Us Help You Cover Every Mile — Including the International Ones

If your trucking operation crosses borders, you need an insurance program built for the realities of international freight. Contact American Insuring Group for the best rates on commercial truck insurance. As independent brokers, we shop the market to find you priced-right coverage that protects every load, in every country you serve.

Call us today at (610) 775-3848 or contact us online to start saving.


Handling Insurance in Lease Agreements

Posted by David Ross on Sat, Jul 11, 2026

Contact us for landlord insurance in Philadelphia, Pittsburgh, Erie, Canonsburg, West Mifflin, Lancaster, Lebanon, and throughout Pennsylvania.

Lease agreements do far more than set the rent and the term. They allocate responsibility for everything that can go wrong on a rental property — and insurance clauses are where much of that allocation actually happens. A lease with clear, well-drafted insurance terms protects both landlord and tenant from disputes about who pays when property is damaged, when someone is injured, or when a covered event interrupts the use of the property. A lease with vague or missing insurance language leaves both parties exposed and creates the conditions for expensive disagreements when claims arise. The right landlord insurance program works in tandem with the lease — not in spite of it.

Clarity in Lease Terms — What the Insurance Clauses Should Say

The insurance section of a residential or commercial lease should answer several specific questions clearly. Who is required to carry insurance? What types and amounts of coverage are required? Who is the additional insured on those policies, if anyone? What happens if a party fails to maintain required coverage? And how is the responsibility for the deductible allocated when both landlord and tenant policies might respond to the same loss? Vague references to 'adequate insurance' or 'reasonable coverage' do not answer these questions and create the very ambiguity that leads to disputes.

Specific dollar limits, named coverage types (general liability, property, business interruption, etc.), and clear procedures for proof of coverage create a lease that actually works. Most well-drafted leases also include a waiver of subrogation provision — a clause that prevents either party's insurer from pursuing the other party for losses that the first party's insurance has already paid. This single provision can prevent significant friction between landlord, tenant, and their respective insurance carriers when a claim is handled.

Required Insurance for Tenants

Residential leases commonly require tenants to carry renters insurance that includes both personal property coverage for their belongings and personal liability coverage for injuries to others or damage to the landlord's property. Typical liability limits required in residential leases range from $100,000 to $300,000, with some landlords requiring higher amounts in upscale markets. Requiring tenants to name the landlord as an additional insured on the liability portion of their renters policy is an increasingly common practice that adds meaningful protection at minimal cost to the tenant.

Commercial leases generally require more substantial coverage. Tenants typically must carry commercial general liability, property insurance on their own improvements and contents, workers compensation if they have employees, and in many cases business interruption insurance. Limits depend on the size of the premises, the nature of the tenant's business, and the landlord's risk tolerance. Commercial leases should also require the tenant to provide a certificate of insurance before move-in, and on each renewal of coverage, naming the landlord as additional insured.

Landlord's Policy Implications

From the landlord's side, the lease's insurance clauses interact directly with the landlord's own insurance program. A landlord policy generally covers the structure, certain landlord-owned contents, loss of rental income, and landlord-side liability — but it typically does not cover the tenant's belongings, the tenant's business operations, or liability arising from the tenant's activities. The lease's tenant-insurance requirements are how the landlord ensures that those gaps are covered by the tenant, not absorbed by the landlord's policy.

Landlords should also pay attention to how their own coverage responds in scenarios where tenant insurance is also in place. Issues such as which policy is primary, how subrogation rights are handled, and what happens when both policies might cover a loss are addressed in the underlying policy language and should be coordinated with the lease terms. An insurance broker who reviews lease language alongside the landlord's coverage can identify mismatches before they become claim disputes. Properly aligned, the lease and the landlord policy work together to protect the property, the rental income, and the relationship between landlord and tenant when something goes wrong.

Protect Your Rental Property with the Right Landlord Insurance

Are you looking for a competitive price on landlord insurance that aligns with your lease structure? Contact our team today. As independent brokers, we shop the market to find you the best deal on quality landlord insurance.

Call American Insuring Group today at (610) 775-3848 or contact us online to start saving.


Tags: Landlord Insurance, lease agreements

Insurance Coverage for Design-Build Risks

Posted by David Ross on Sat, Jul 04, 2026

Contact us for design-build insurance in Philadelphia, Pittsburgh, Allentown, Erie, Lancaster, Reading, and anywhere in Pennsylvania.Design-build projects have become an increasingly popular delivery method for everything from commercial buildings to public infrastructure. In a design-build arrangement, a single entity is responsible for both the design and the construction of a project — streamlining communication, compressing timelines, and giving the owner a single point of accountability. But this integrated delivery model creates a unique risk profile that does not fit neatly into traditional construction insurance frameworks. The same firm is now responsible for design errors and construction defects, which means liability that was once split between two separate parties now sits with one. The right contractor insurance program is what makes that integrated risk manageable rather than dangerous.
Unique Risks Covered Under Design-Build Insurance

The defining characteristic of a design-build project is that the design professional and the construction contractor are either the same firm or operate under a single contractual umbrella. This eliminates the traditional separation between design liability and construction liability — and with it, the traditional structure of two separate insurance programs covering two separate parties. The design-build entity needs coverage that addresses both sides of the risk under one coordinated framework.

Key exposures that design-build insurance must address include professional liability for design errors and omissions; general liability for bodily injury and property damage during construction; builder's risk for damage to the project itself; and pollution liability for environmental exposures created during the work. In addition, the integrated nature of design-build creates the possibility of disputes where it is unclear whether a defect originated in design, in construction, or in the interaction between the two. Insurance programs built for traditional construction often leave gaps in exactly this gray area. Design-build coverage is engineered to close them.

Policy Options for Design-Build Projects

Design-build firms generally have two main paths for structuring their insurance. The first is a coordinated program of separate policies — typically professional liability, general liability, builder's risk, and any required specialty coverages — written so that the policies dovetail and respond consistently to claims. The second is a project-specific or wrap-up policy that combines multiple coverages for a single project under one program, often with all parties named as insureds.

Each approach has tradeoffs. The coordinated program is generally simpler to administer for a firm doing many small to medium projects. The project-specific wrap-up makes more sense for larger, more complex projects where the cost and complexity of negotiating individual contractor policies would be significant. Some design-build firms use both — running a baseline program for smaller work and layering project-specific policies on top for the larger jobs. The right answer depends on project size, owner requirements, and the firm's risk tolerance. An experienced insurance broker can help design a program that fits the actual work pipeline rather than a generic template.

Handling Design-Build Liability When Claims Arise

When something goes wrong on a design-build project, the path to resolution is different from a traditional design-bid-build dispute. There is no second party to point at — the same firm is responsible for both ends of the work. This means the firm's insurance program has to be ready to respond to claims that may involve design, construction, or both simultaneously, often without a clear factual line between them.

Practical claim management on design-build projects depends on several factors: policy language that clearly addresses combined design and construction exposures; coordinated defense between the professional liability and general liability carriers (or a single carrier handling both); thorough documentation throughout the project lifecycle to support causation analysis; and an insurance broker who can advocate effectively when coverage questions arise. The strongest position for a design-build firm is to anticipate these issues when the insurance program is structured — long before the first claim is filed. A program designed for design-build risks responds the way the firm needs it to. A program patched together from traditional construction templates often does not.

Let Us Help You Build the Right Design-Build Insurance Program

Do you have questions about design-build coverage? Contact American Insuring Group for the best rates on integrated construction insurance. As independent brokers, we shop the market to find you the right policy for the way you actually deliver projects.

Call us today at (610) 775-3848 or contact us online to start saving.

Tags: Construction Insurance, Contractor Insurance, design-build insurance

Workers’ Compensation Insurance for Remote Employees

Posted by David Ross on Sun, Jun 21, 2026

Call us for workers compensation insurance for remote employees in Philadelphia, Reading, Lancaster, York, Erie, Pittsburgh, and anywhere in PA

As remote and hybrid work become the norm, employers must decide how to keep things safe and compliant. One specific area is workers’ compensation for these remote workers. The traditional workplace had clear lines, while the home office created gray areas that needed careful policy planning and risk management.

Extent of Coverage

Workers’ compensation typically covers injuries and illnesses that occur out of and in the course of employment — no matter where the work is done. If you’re an employee who works remotely, this means that injuries you sustain while doing your job at home may still be covered.

But when you move outside a controlled office environment, it can be more difficult to define what is “work” and what is not. For example, if an employee trips over a piece of equipment at work, they may have a legitimate claim, but an injury sustained during a personal activity, such as preparing lunch, likely wouldn’t. The critical element is whether the activity is directly related to job duties.

Employers should remove ambiguity by explicitly defining work hours, the workspace, and job duties. Documentation is critical in evaluating teleworker claims.

Policy Modifications

Review your workers’ compensation policies, classifications, payroll reporting, and job descriptions to ensure remote jobs are correctly captured and properly covered for off-site workers.

Employers should also create agreements that outline the company's expectations regarding safety, ergonomics, and accident reporting. They will be valuable reference documents for determining whether a claim is covered.

Businesses must also inform their employees of any policy changes so they know and understand their rights and responsibilities. Consistent training sessions and induction materials for off-site workers can increase compliance and reduce exposure to risk.

Managing Offsite Risks

Managing remote risks starts with preventing accidents. Although employers have less control over the remote environment, they can promote safety by offering protocols and materials. Ergonomic recommendations, checklists, or stipends for proper office equipment can be very effective in reducing injury risk.

Routine check-ins, virtual assessments, or self-certification forms can also help ensure employees are continuing to work safely. It is also important to encourage employees to report injuries promptly, as delays can complicate claims and increase costs.

Technology can assist as well. Digital reporting tools, incident-tracking systems, and communication platforms permit employers to respond quickly to issues—even from a distance.

Ultimately, workers’ compensation for remote employees needs a balance of flexibility and structure. Employers can safeguard their workforce and organization in a shifting work environment by explicitly defining coverage, revising policies, and diligently addressing off-site risks.

We Can Help You with Workers’ Compensation Insurance for Remote Workers

Looking for an experienced and reliable workers' compensation insurance agency? Contact American Insuring Group online, or call (800) 947-1270 or (610) 775-3848. Our independent agents will find you the perfect policy at an excellent price.

Contact us today to get started!