Insurance Savings and News You Can Use
Join the Conversation!

Landlord Liability Insurance: Protecting Yourself From Tenant Lawsuits

Posted by David Ross on Sat, Nov 14, 2026

Call us for Landlord Liability Insurance in Philadelphia, Pittsburgh, Allentown, Erie, Lancaster, York, Harrisburg, and throughout Pennsylvania.

What Landlord Liability Coverage Actually Pays For

Liability coverage responds to two things: money you are legally obligated to pay someone else, and the cost of defending you. The second is the part landlords underestimate.

Defense costs are typically paid outside your liability limit, so attorney fees do not erode the money available to settle. A lawsuit that is ultimately dismissed still generates months of legal work, and without coverage that expense comes straight out of your rental income regardless of the outcome.

The coverage also pays limited medical expenses without any finding of fault — a small separate limit meant to resolve minor injuries before they become lawsuits.

What Kinds of Tenant Lawsuits Does It Cover?

The claims that reach landlords cluster around a few recurring scenarios, most involving a physical condition the owner knew about or should have known about.

Slip-and-fall injuries lead the list — unlit stairwells, icy walkways, loose handrails, uneven porch treads. Falls from defective porches follow, a live concern on Reading's older housing stock where original wooden porches have been repaired in layers over decades. Dog bites by a tenant's animal in a common area, injuries from failing electrical or heating systems, and lead-paint claims on pre-1978 buildings round out the pattern.

These claims are uncommon but costly. Data compiled by the Insurance Information Institute from ISO, a Verisk Analytics business, shows liability was only 1.7% of homeowners claims in 2023, yet liability claims averaged $29,880 each across 2019-2023 — roughly twice the average water-damage claim. Low frequency and high severity is exactly the risk insurance exists to handle.

Where Liability Coverage Stops

Liability insurance covers accidents, not business decisions and not intentional acts. Intentional acts by the landlord are excluded. So are contractual disputes over the lease, security deposits, and rent — those are breach-of-contract matters, not bodily injury. Most habitability and wrongful-eviction claims fall outside standard liability coverage as well. Claims brought by your own employees belong to workers' compensation, and damage to the building itself is a property claim regardless of who caused it.

Because much landlord-tenant conflict is legal rather than physical, many owners add legal expense coverage for landlords, which reaches disputes liability coverage was never designed to cover.

How Much Liability Coverage Should a Landlord Carry?

Base your limit on what you could lose, not on the policy default. Many landlord policies still carry a limit chosen years ago and never revisited — often $300,000, a figure a single serious injury claim can exceed.

A practical approach is to set the underlying limit at $500,000 or $1 million, then add an umbrella policy above it. Umbrella coverage is inexpensive per dollar of protection because it responds only after the underlying limit is exhausted, and it usually extends across multiple properties at once.

Owners holding several doors should also check how the properties are titled. Whether a building sits in your own name or in an LLC changes which policy responds, and the insurance should be structured to match the ownership rather than assumed to follow it.

Reducing the Odds of a Claim

Liability coverage is the backstop. Documented maintenance is the first line, and it makes a claim defensible when one arrives.

Inspect and document common areas on a schedule — stairs, handrails, walkways, lighting, porches — with dated photographs. Respond to tenant repair requests in writing and keep the record, since a documented prompt response is strong evidence against a negligence allegation. Clear snow and ice promptly and log it. Require renters insurance in every lease, and keep lead-paint disclosures on file for pre-1978 properties.

If a claim does occur, report it immediately. Every policy carries a duty to notify the carrier without unreasonable delay, and late reporting is one of the few ways an otherwise covered claim can be compromised. Our walkthrough of the claims process for landlords covers what happens next.

Frequently Asked Questions

Does landlord liability insurance cover legal defense costs?

Yes. Your insurer has a duty to defend covered claims, and defense costs are typically paid in addition to your liability limit rather than subtracted from it. That means attorney fees do not reduce the money available to settle. The duty to defend usually applies even to claims that prove groundless, provided the allegation falls within the policy's coverage.

How much landlord liability coverage should I carry?

Most advisors suggest at least $500,000 to $1 million on the underlying policy, with an umbrella layered above it. The right figure depends on your equity, your other assets, and how many units you own. Because umbrella coverage costs little per dollar of protection, raising total limits is usually one of the least expensive risk decisions a landlord can make.

Does landlord liability insurance cover dog bites on my rental property?

Sometimes, and it depends on the policy. Many carriers exclude bites by specific breeds or exclude animal liability entirely, and a tenant's dog may be treated differently from your own. Requiring renters insurance and a written pet addendum shifts much of that exposure to the tenant. Confirm the animal liability language with your agent rather than assuming coverage.

Am I liable if a tenant's guest is injured at my rental?

You can be, if the injury resulted from a condition of the property you were responsible for maintaining — a broken stair, an unlit hallway, an icy walkway. Guests generally have the same standing to sue as tenants. Liability coverage responds to those claims, and documented maintenance records are the best defense against a negligence allegation.


Review Your Liability Limits With an Independent Agent

Liability limits are the easiest part of a landlord policy to leave untouched for a decade, and the most expensive to find inadequate after a claim. Checking the limit takes minutes; raising it usually costs far less than owners expect.

American Insuring Group is an independent agency in Reading, Pennsylvania, serving landlords throughout Berks County. We compare liability and umbrella prices and options across multiple carriers rather than quoting one company.

Learn more about our landlord insurance coverage, and then contact us at (610) 775-3848 or connect with us online to review your limits.

Tags: Landlord Insurance, Landlord Liability Insurance

Landlord Insurance Coverage Explained: What's Included and What's Not

Posted by David Ross on Sat, Nov 07, 2026

aig-landlord-insurance-coverage-explained-rental-policy

The Five Coverage Blocks Inside a Landlord Policy

Every landlord policy is assembled from a short list of coverage parts, each with its own limit and its own rules. Reading the policy means knowing which block a given loss falls into — and which block runs out first.

Dwelling Coverage

This rebuilds the structure after a covered loss. The limit should equal what a contractor would charge to reconstruct the building today, not the purchase price and not the market value. On older masonry row homes, reconstruction cost frequently exceeds market value by a wide margin, which is how well-intentioned owners end up underinsured.

Other Structures

Detached items on the same parcel — a garage, a shed, fencing, a retaining wall — fall here. The limit is usually set automatically as a percentage of the dwelling limit, commonly around 10%, rather than chosen deliberately. If you have a detached two-car garage behind a modest row home, that default is worth checking.

Landlord's Personal Property

Property you own and keep at the rental for the tenant's use is covered: the refrigerator and range you supply, a washer and dryer, window treatments, lawn equipment stored on site, furnishings in a furnished rental. This limit is typically modest by default and is one of the easiest to raise.

Liability Coverage

Liability responds when a tenant, a guest, a delivery driver, or a passerby is injured on your property and you are alleged to be at fault. It pays judgments and settlements up to the limit, and it pays defense costs — which in a contested landlord case are often the larger number.

Fair Rental Value

When a covered loss makes a unit uninhabitable, this replaces the rent you are not collecting during repairs. It is capped either as a percentage of the dwelling limit or as a fixed number of months. Match that cap against a realistic rebuild timeline for your building type, not a best case.

Which Perils Are Actually Covered?

Most landlord policies today are written on an open-perils basis for the structure, meaning the building is covered against any cause of loss the policy does not specifically exclude. That is a broader promise than the alternative, which lists covered perils individually and leaves everything else out.

The losses that actually happen are less exotic than owners expect. Industry data compiled by the Insurance Information Institute from ISO, a Verisk Analytics business, shows that 5.3% of insured homes had a claim in 2023, and that wind and hail accounted for 42.5% of those claims, water damage and freezing 22.6%, and fire and lightning 21.6%.

For a Berks County landlord that ordering is instructive. Wind events and winter freeze damage — a burst supply line in an unheated second-floor bathroom during a January cold snap — are far more likely to generate a claim than the catastrophic fire most owners picture when they think about insurance. Coverage decisions should be weighted accordingly. Our overview of the basics of landlord insurance covers the underlying structure in plain language.

What Landlord Insurance Does Not Cover

Exclusions generate more disputes than coverages do, and the significant ones are consistent from carrier to carrier.

Flood. Excluded from every standard property policy. Coverage requires a National Flood Insurance Program policy or a private flood market alternative. Properties near the Schuylkill River and the creeks crossing Berks County should price it regardless of flood-zone designation.

Earth movement. Sinkholes, landslide, and earthquake are excluded and require separate coverage. Carbonate bedrock across parts of eastern Pennsylvania makes sinkhole activity a real consideration rather than a formality.

Your tenant's personal property. Nothing your tenant owns is covered by your policy. Requiring renters insurance in the lease, with proof at signing and renewal, is the standard answer.

Wear, tear, and deferred maintenance. Insurance pays for sudden and accidental loss. A roof that has degraded over fifteen years, a slow leak that rotted a subfloor, and failing original wiring are maintenance obligations, and carriers apply that line firmly.

Mold, in most cases. Mold is usually excluded or sharply sublimited unless it results directly from a covered water loss that was reported and remediated promptly. Delay in reporting is frequently what converts a covered water claim into an uncovered mold claim.

Losses during extended vacancy. Once a building has been vacant beyond the period stated in the policy, commonly 30 or 60 days, vandalism, glass breakage, and water damage are typically suspended. The policy stays in force but narrows. See insurance for unoccupied properties for how to keep that coverage intact between tenants.

Does the Policy Cover Damage Caused by Your Tenant?

Sometimes, and the distinction is sudden accidental damage versus accumulated abuse. A tenant who leaves a bathtub running and floods the unit below has caused a sudden accidental water loss, which is generally covered. A tenant who lets damage build over two years of occupancy has created a maintenance and security-deposit problem, which is not.

Deliberate destruction by a tenant sits in between. Some policies exclude vandalism by an insured party's tenant; others cover it or offer it as a buyable endorsement, occasionally labeled malicious mischief or tenant vandalism. This is a specific question to ask about your specific policy, because the answer genuinely varies.

Where a tenant dispute escalates into litigation, the cost is usually legal rather than physical. Dedicated legal expense coverage for landlords addresses that exposure directly, and it functions differently from the defense costs bundled into liability coverage.

Optional Coverages That Close the Gaps

Most of the exclusions above have a corresponding endorsement, and they are generally inexpensive relative to what they cover.

Water backup and sump overflow covers water entering through sewers and drains or from a failed sump pump — one of the most common losses in older basements with original lateral connections.

Equipment breakdown covers mechanical and electrical failure of building systems such as boilers, furnaces, and electrical panels, which the base policy treats as maintenance

Ordinance or law funds the code upgrades a rebuild triggers on an older building, closing the gap between restoring what existed and satisfying current code.

Umbrella liability extends your liability limit in million-dollar increments above the underlying policy, typically at a low cost per dollar of protection.

Vacancy permit preserves the coverages that would otherwise suspend during an extended turnover or renovation.

How Coverage Changes by Property Type

The coverage blocks stay the same from property to property, but which policy form they sit on — and which limits matter most — shifts with what you own.

Single-family rentals are typically written on a DP-3 dwelling fire form. The pressure points are an accurate reconstruction limit and a fair rental value cap long enough to cover a full rebuild, since losing the building means losing 100% of the income from that address.

Two-to-four-unit buildings, the backbone of the rental stock in Reading and the surrounding boroughs, usually remain on a dwelling form but demand closer attention to liability and to shared systems. One boiler, one electrical service, and a common stairwell mean a single failure can affect every tenant at once, and common areas are where most injury claims originate.

Mixed-use buildings — a storefront below, apartments above — generally cannot be insured on a residential dwelling form at all. They require a commercial policy that contemplates both occupancies, and the commercial tenant's own operations become part of your risk profile.

Larger portfolios are often best written on a single commercial package policy covering every property on one schedule, which simplifies renewals and frequently lowers the total premium compared with separate policies per address.

How to Read Your Declarations Page

The declarations page is the two-page summary at the front of the policy, and it answers most coverage questions faster than the policy language does. Four items are worth checking every renewal.

First, the policy form — DP-3, DP-1, or a commercial form — which tells you how broad the peril coverage is. Second, whether settlement is on a replacement cost or actual cash value basis, including any separate roof schedule that depreciates by age. Third, the fair rental value limit and its time cap. Fourth, the liability limit, which on older policies is often still set at a figure chosen years ago and never revisited.

Two more entries repay a careful look. The deductible applies per occurrence, and some policies carry a separate, higher wind and hail deductible expressed as a percentage of the dwelling limit rather than a flat amount. On a $300,000 building, a 2% wind deductible is $6,000 — a very different number than the $1,000 printed at the top of the page.

Check the named insured as well. If you have moved a property into an LLC since the policy was written, and the declarations page still shows your personal name, the entity that owns the building may not be the entity the policy protects. That mismatch is common, easy to correct, and genuinely damaging if it is discovered during a claim rather than before one.

If a loss does occur, knowing these numbers before you call turns the first conversation with an adjuster into a much shorter one. Our walkthrough of the claims process for landlords covers what happens after that call.

Frequently Asked Questions

Does landlord insurance cover loss of rental income?

Yes, through fair rental value coverage, but only when the unit is uninhabitable because of a covered loss. Rent lost to a tenant who simply stops paying, or to an ordinary vacancy between leases, is not covered. The benefit is capped either as a percentage of the dwelling limit or by a stated number of months, so check that cap against a realistic repair timeline.

Is flood damage covered by a landlord policy?

No. Flood is excluded from every standard property policy, including landlord and dwelling fire policies. Coverage must be purchased separately through the National Flood Insurance Program or a private flood carrier. Being outside a mapped high-risk flood zone reduces the premium but does not eliminate the exposure, and a significant share of flood claims come from outside those zones.

Does a landlord policy cover the appliances I provide?

Yes. Appliances you own and supply for the tenant's use fall under landlord's personal property coverage, which also picks up items like window treatments and on-site lawn equipment. The default limit is often modest, so if you furnish units or supply full appliance packages across several doors, ask your agent to raise it to match what you actually own.

What is the difference between actual cash value and replacement cost on a rental policy?

Replacement cost pays what it costs to replace damaged property today. Actual cash value pays replacement cost minus depreciation for age and wear. On a twenty-year-old roof the gap can be most of the claim. Many carriers now apply actual cash value to roofs specifically, even on policies that are otherwise replacement cost, so check the roof schedule separately.

Have Your Coverage Reviewed Before Renewal

Coverage gaps are invisible until a claim finds them. A policy review takes very little time and is the only reliable way to confirm that your limits, your policy form, and your endorsements match how the property is actually used.

American Insuring Group is an independent agency based in Reading, Pennsylvania. We compare landlord and rental-property coverage across multiple carriers to find you the right coverage at a great price, rather than quoting one company's product — which matters on older Berks County buildings, where carrier appetite and roof-settlement rules vary considerably.

Learn more about our landlord insurance coverage, then contact us online or call us at (610) 775-3848 for a review of your current policy.

Tags: Landlord Insurance

The Complete Guide to Landlord Insurance for Rental Property Owners

Posted by David Ross on Sat, Oct 31, 2026

Contact us for landlord insurance for rental properties in Berks County, Philadelphia, Pittsburgh, Harrisburg, Lancaster, Allentown, and anywhere in PA

Why a Rented-Out Property Needs Its Own Policy

The moment a tenant moves in, the building stops being a residence and becomes a business asset — and most homeowners policies are written to exclude exactly that use. Insurers price a homeowners policy on the assumption that the owner lives there, maintains it daily, and is the only person with a legal claim against the owner for injuries on the premises. Renting the property out breaks all three assumptions

This matters more than most owners expect, because the failure mode is not a smaller payout — it is a denied claim. If a fire damages a rental still insured under a homeowners policy, the carrier can deny the loss outright on the grounds that the property was not occupied as described on the application

The distinction is worth understanding in detail before you shop, and we walk through it side by side in landlord insurance vs. homeowners insurance. The short version: the two policies share a family resemblance and almost nothing else where it counts.

This is not a niche concern. Individual investors still own the majority of America's single-family rental housing — 59.6% of single-family rental properties in 2024, down from 70.9% in 2021, according to Chandan Economics' February 2026 analysis of the U.S. Census Bureau's 2024 Rental Housing Finance Survey. Most landlords in this country are ordinary people with one, two, or a handful of doors, buying coverage without a risk manager on staff.

The Three Core Parts of a Landlord Policy

Nearly every landlord policy is built from three coverage blocks: the building itself, your liability exposure, and the rent you would lose if the unit became uninhabitable. Understanding what each one does — and where each one stops — is the whole job.

Dwelling and Other Structures

This is the coverage that rebuilds the building after a covered loss such as fire, wind, hail, or certain kinds of water damage. It is written to a stated limit that should reflect what it would cost to reconstruct the property at current local labor and material prices, not what you paid for it and not what Zillow thinks it is worth.

That distinction trips up a lot of owners. A brick row home in Reading might sell for well under its replacement cost, because the land and the market set the sale price while a contractor sets the rebuild price. Insuring to market value on that kind of property is one of the most common ways landlords end up underinsured without knowing it.

"Other structures" picks up detached items on the same lot — a garage, a shed, a fence, a retaining wall. It is usually a percentage of the dwelling limit rather than a chosen number, so check whether that default covers what is standing on your parcel.

Liability Coverage

Liability responds when someone who is not you is hurt on the property, or their property is damaged, and you are alleged to be responsible. It pays settlements and judgments up to your limit, and — critically — it pays for the attorney who defends you, usually without eroding that limit.

Liability claims are rare and expensive, which is the worst combination for anyone tempted to skip the coverage. Industry data compiled by the Insurance Information Institute from ISO, a Verisk Analytics business, shows liability made up just 1.7% of homeowners claims in 2023, but liability claims averaged $29,880 apiece across 2019-2023 — roughly double the average water-damage claim.

Because the legal costs are frequently the larger half of a landlord dispute, many owners add dedicated legal expense protection on top. We cover how that works in legal expense coverage for landlords.

Loss of Rental Income

If a covered loss makes the unit uninhabitable, this coverage replaces the rent you are not collecting while repairs happen. It is often called fair rental value, and it is the coverage landlords are most likely to discover they needed only after a fire.

The important details are the limit and the clock. Some policies cap the benefit at a percentage of the dwelling limit; others cap it at a number of months. A four-unit building with a six-month rebuild timeline and a four-month rental-income cap leaves you carrying the mortgage on your own for the last two months.

Which Policy Form Will Your Rental Actually Be Written On?

Most single-family and small residential rentals are insured on a dwelling fire policy — commonly a DP-3 — rather than the HO-3 homeowners form used for owner-occupied houses. The dwelling fire family was built for exactly this situation: a residential structure the owner does not live in.

The DP-3 is the broadest of the dwelling forms and the one most landlords should want. It covers the structure on an open-perils basis, meaning it insures against any cause of loss the policy does not specifically exclude, which is a materially wider promise than a list of named perils.

Older or narrower forms still circulate. A DP-1 covers a short named-perils list and frequently settles losses at actual cash value — replacement cost minus depreciation — which on a thirty-year-old roof can mean a payout that does not come close to funding a new one. A DP-2 sits between the two. The form matters as much as the limit, and it is not always obvious from the declarations page.

Larger portfolios, mixed-use buildings, and anything with meaningful commercial square footage typically move onto a commercial package policy instead, where the building, liability, and income coverages are assembled individually. For a plain-language walk through the fundamentals, see the basics of landlord insurance.

What Does Landlord Insurance Cost in Pennsylvania?

Landlord policies generally run somewhat higher than a comparable homeowners policy on the same building — the widely cited rule of thumb is roughly 15% to 25% more — because tenant occupancy carries more liability exposure and less day-to-day owner oversight. Your actual premium depends on factors specific to the property rather than any published average.

The variables that move the number most are replacement cost, construction type, roof age and condition, distance to a fire hydrant and staffed fire company, claims history on both the property and the owner, the deductible you select, and your liability limit. In older housing stock, the condition of the electrical service, the plumbing, and the heating system carries real weight.

Berks County rentals have a particular profile here. A lot of the inventory in Reading, Mount Penn, and West Reading is early-twentieth-century masonry with knob-and-tube remnants, updated in layers by different owners over decades. Carriers price that uncertainty. Documented electrical and plumbing upgrades are frequently the single most effective thing a landlord can show an underwriter.

Bundling policies, raising the deductible to a level you could actually absorb, and consolidating multiple properties with one carrier are the levers that matter. Chasing a lower premium by quietly reducing the dwelling limit is not a saving — it is a deferred loss.

Coverage Gaps That Catch Landlords Off Guard

The exclusions cause more disputes than the coverages do. A landlord policy is a broad contract with specific holes in it, and the holes are predictable enough to plan around.

Flood is not covered. No standard property policy includes flood, and that includes landlord policies. Coverage comes from the National Flood Insurance Program or a private flood market. Along the Schuylkill River corridor and the creeks running through Berks County, this is a live question rather than a theoretical one, and being outside a mapped high-risk zone is not the same as being safe.

Earth movement is not covered. Sinkholes, landslides, and earthquake damage require separate treatment. Parts of eastern Pennsylvania sit on carbonate bedrock where sinkhole activity is a genuine consideration.

Your tenant's belongings are not covered. Your policy insures your building and anything you own inside it. A tenant's furniture, electronics, and clothing are the tenant's problem unless they carry renters insurance — which is why requiring it in the lease is standard practice for experienced owners.

Wear, tear, and deferred maintenance are not covered. Insurance pays for sudden, accidental loss. A roof that has quietly failed over fifteen years is a maintenance expense, and carriers are increasingly firm about that line.

Ordinance or law costs may not be fully covered. If a covered loss triggers a rebuild, current code may demand upgrades the old building did not have. Without ordinance-or-law coverage, the gap between "restore what was there" and "satisfy today's code" lands on you.


What Happens to Your Coverage When the Property Sits Empty?

Most property policies restrict or suspend key coverages once a building has been vacant beyond a stated period — commonly 30 or 60 consecutive days — and vandalism, glass breakage, and water damage are usually the first to go. The policy does not cancel; it quietly narrows.

This is the gap that catches otherwise careful landlords, because vacancy is a normal part of the business rather than an emergency. A tenant leaves, you take eight weeks to renovate the kitchen and re-list, and somewhere in the middle of that ordinary turnover your effective coverage changed without any notice arriving in the mail.

The fix is a vacancy permit endorsement or a dedicated vacant property policy for the duration. Neither is exotic, both are inexpensive relative to the exposure, and both require you to call before the clock runs out rather than after something happens. We go through the mechanics in insurance for unoccupied properties.

Major renovation raises a second issue. Once work goes beyond cosmetic updates into structural change, some carriers want the project on a builders risk or renovation policy instead, because an open building with contractors coming and going is a different risk than a closed one.
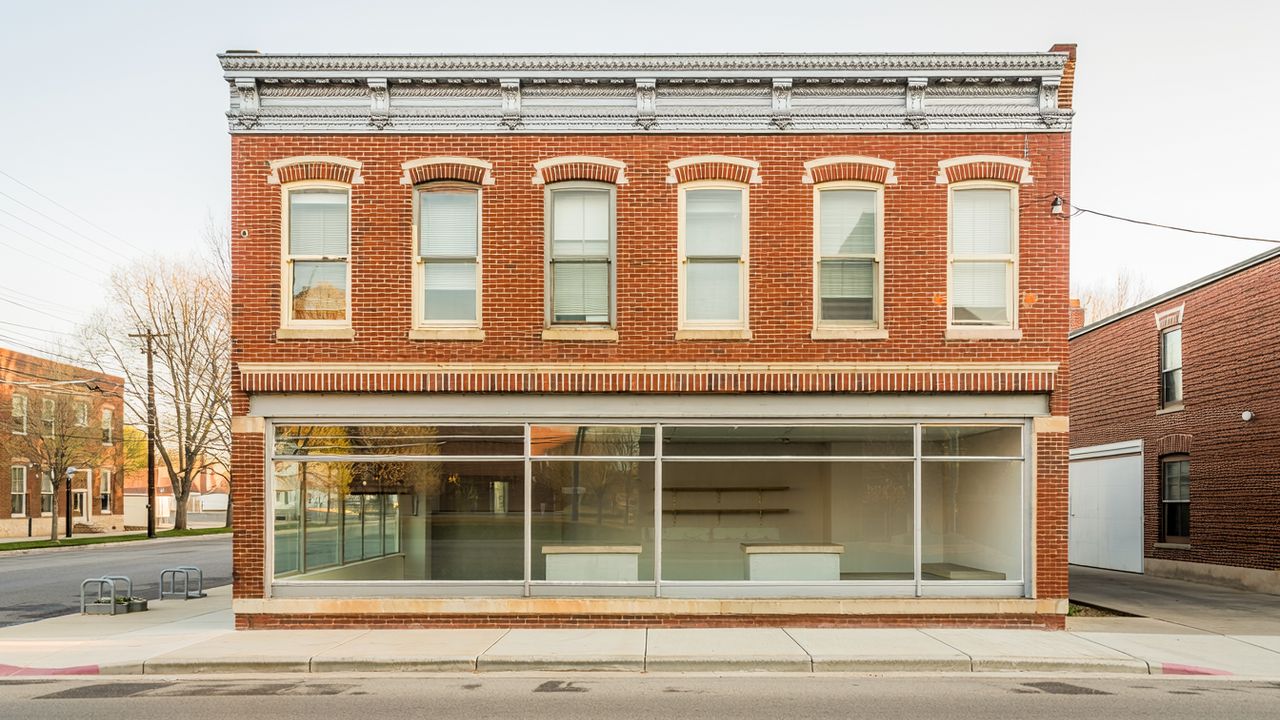
example of a mixed use multi-unit property requiring landlord insurance

Multi-Unit and Mixed-Use Properties in Berks County

Reading's housing stock skews heavily toward rental, and the city's building inventory reflects a century of conversions. Census Bureau QuickFacts puts Reading's owner-occupied housing rate at 40.6% for 2020-2024 — meaning the clear majority of the city's occupied homes are rented, and a large share of those sit in buildings that were never purpose-built as rentals.

Two-to-four-unit conversions of single-family row homes are extremely common here, and they raise questions a single-family policy does not. Shared heating systems, a single electrical service feeding multiple units, common stairwells, and shared egress all concentrate risk in ways underwriters price carefully.

Mixed-use is the other Berks County staple — a storefront at street level with apartments above. That building usually cannot be insured on a residential dwelling form at all. It needs a commercial policy that contemplates both the retail operation below and the residential occupancy above, and the commercial tenant's own liability coverage becomes part of your risk picture.

If you own several properties, ask specifically about writing them on a single schedule under one policy. It usually simplifies administration, can reduce the total premium, and it prevents one property quietly lapsing because a renewal notice went to an old address.

Endorsements Worth Adding to a Landlord Policy

The base policy is a starting point. A handful of endorsements close the gaps that generate the most expensive landlord surprises, and most of them cost a fraction of what the underlying coverage costs.

Water backup and sump overflow. Standard property coverage excludes water that backs up through sewers and drains or overflows from a failed sump pump. In older Berks County basements with original lateral connections, this is one of the most frequent losses there is, and the endorsement is typically inexpensive.

Equipment breakdown. This covers the mechanical and electrical failure of building systems — boilers, furnaces, central air, electrical panels — which the base policy treats as a maintenance issue rather than a covered peril. On a multi-unit building with a shared heating plant, a mid-January boiler failure is both a repair bill and a habitability problem.

Umbrella liability. An umbrella sits above your landlord policy's liability limit and picks up where it ends, usually in million-dollar increments. Given that liability claims are infrequent but severe, this is generally the highest-value dollar a landlord spends on insurance.

Tenant discrimination and wrongful eviction. Some markets offer coverage for fair-housing and eviction-related claims. These are defense-cost exposures more than judgment exposures, and defense costs alone can be substantial.

How Landlord Claims Actually Get Paid

A landlord claim moves faster and settles higher when the documentation exists before the loss rather than being reconstructed after it. That is the single largest controllable variable in the process.

Build the file while everything is intact. Photograph every unit at each turnover. Keep the signed leases, the rent roll, and the receipts for every capital improvement — a new roof, a rewire, a boiler replacement. When a claim arrives, that folder is the difference between a fast settlement and a long argument about what was there and what condition it was in.

Report losses promptly. Every policy carries a duty to notify the carrier without unreasonable delay and a duty to protect the property from further damage. Tarping a roof or shutting a water main is both good practice and a contractual obligation.

For loss-of-rent claims specifically, the adjuster will want the lease and a documented rent history, not an estimate of what the unit could fetch. A unit rented below market settles at the lease rate. Our walkthrough of the claims process for landlords covers the sequence in more detail.

A Practical Coverage Checklist

Before you bind a policy or renew an existing one, work through this list with your agent — most coverage failures trace back to one of these items never being asked about.

  • Confirm the policy form. DP-3 or broader for most residential rentals; commercial for mixed-use and larger portfolios. Ask which form is on the declarations page rather than assuming.

  • Confirm replacement cost, not actual cash value — on both the building and the roof. Roof settlement schedules that depreciate by age are increasingly common and are worth reading closely.

  • Set the dwelling limit to reconstruction cost, reviewed annually. Construction costs have moved sharply in recent years, and a limit set five years ago is probably no longer accurate.

  • Check the loss-of-rent limit and its time cap against a realistic rebuild timeline.

  • Review your liability limit against your total exposure, and price an umbrella policy over the top.

  • Add ordinance-or-law coverage on any older building.

  • Ask about the vacancy provision and know the exact day count before coverage narrows.

  • Require renters insurance in every lease, with proof at signing and at renewal.

  • Evaluate flood separately, regardless of what the flood map says.

Frequently Asked Questions

How much does landlord insurance cost for a single rental property?

Premiums vary widely by property rather than following a national average. As a rule of thumb, a landlord policy runs roughly 15% to 25% more than a homeowners policy on a comparable building, because tenant occupancy adds liability exposure. Replacement cost, roof age, construction type, deductible, liability limit, and claims history drive the final number more than the property's market value does.

Is landlord insurance required by law in Pennsylvania?

Pennsylvania does not require landlords to carry property or liability insurance by statute. In practice it is close to mandatory anyway: mortgage lenders require property coverage as a condition of the loan, and many municipal rental-licensing programs and housing-authority payment contracts require proof of liability coverage before a unit can be occupied.

Does landlord insurance cover the tenant's belongings?

No. A landlord policy covers your building, your liability, and property you own inside the unit, such as appliances you supply. Tenant-owned furniture, electronics, and clothing are covered only by the tenant's own renters insurance. This is why experienced owners require renters insurance in the lease and collect proof of it at signing and at every renewal.

How many rental properties can I put on one landlord policy?

Several, in most cases. Carriers commonly write multiple properties on a single scheduled policy, which simplifies billing and renewals and often reduces total premium compared with separate policies. Once a portfolio grows past a handful of doors, a commercial package policy is usually the better structure. Ask your agent to compare both approaches on your specific schedule.


Get Your Rental Property Coverage Reviewed Today!

Most of the coverage failures described above are invisible until a claim exposes them — and by then the policy language is fixed. A review before renewal costs nothing and is the only reliable way to find out whether your dwelling limit, your policy form, and your vacancy provision actually match the way you use the property.

American Insuring Group is an independent agency near Reading, Pennsylvania. Because we are independent, we compare landlord and rental-property coverage across multiple carriers rather than quoting a single company's product, which matters a great deal on older Berks County housing stock where carrier appetite varies widely. Learn more about our landlord insurance coverage, then call us at (610) 775-3848 or contact us online to have your current policy reviewed against the checklist above.
Tags: Landlord Insurance, Rental Property Insurance

Landlord Insurance for Vacant and Between-Tenant Rentals

Posted by David Ross on Sat, Oct 03, 2026

Call AIG for best landlord insurance in Philadelphia, Pittsburgh, Reading, Harrisburg, Erie, Allentown, York, and throughout Pennsylvania

A standard landlord insurance policy often reduces or suspends coverage once a rental property sits empty for a set number of consecutive days — commonly 30 or 60. To stay protected while a unit is vacant or between tenants, most landlords need a vacancy permit endorsement or a separate vacant property policy. Leaving that gap unaddressed is one of the most common and costly mistakes rental property owners make.

An empty rental feels lower-risk than an occupied one, but insurers see it the opposite way. Vacant buildings are more exposed to vandalism, theft, undetected water damage, and delayed discovery of problems because no one is there to notice a leak, a break-in, or a failing furnace. That is why the vacancy clause buried in most landlord policies can quietly leave an owner uninsured at the worst possible moment. With the U.S. rental vacancy rate at 7.3% in the first quarter of 2026, per U.S. Census Bureau data reported by the Federal Reserve, vacancy is a normal part of owning rentals — which makes understanding how your landlord insurance [https://www.aigltd.com/landlord-insurance] treats it essential.

Does Landlord Insurance Cover a Vacant Property?

A standard landlord policy generally does cover short, expected gaps between tenants, but coverage typically changes once a property has been vacant beyond the policy's stated vacancy period. After that point, many policies limit or exclude key perils — most notably vandalism, glass breakage, water damage, and theft.

This is the trap that catches many owners. The property is still insured "on paper," but the specific losses most likely to happen to an empty building are exactly the ones the vacancy clause carves out. A pipe bursts in a unit that has been empty for 45 days, and the claim is denied because the policy suspended water-damage coverage after 30 days of vacancy. Liability can shift as well: some policies also narrow the coverage that would respond if a trespasser or contractor is injured on a property left standing empty. The lesson is to read the vacancy provision in your own policy before a unit goes empty, not after a loss. Vacancy definitions and time limits vary widely between insurers and policy forms, so never assume yours matches a competitor's or a prior policy's terms.

How Long Can a Rental Sit Vacant Before Coverage Changes?

Most landlord and dwelling policies define a vacancy trigger of 30 or 60 consecutive days, after which certain coverages are reduced or suspended. The exact number, and which perils are affected, is written into your specific policy — there is no universal standard.

Because that window is shorter than many owners expect, a routine turnover can cross the line without anyone realizing it. Consider a Berks County landlord renovating a Reading duplex between tenants: if the work stretches past the policy's 30- or 60-day threshold, the property may quietly lose vandalism and water-damage protection right when the building is most exposed. The fix is usually straightforward — a vacancy permit endorsement extends coverage through a known vacancy, and a dedicated vacant property policy covers longer or repeated vacancies. Both are far cheaper than an uncovered loss. If you know a unit will be empty for an extended period, notify your broker before the vacancy begins so coverage can be arranged in advance.

What Is Vacant Property Insurance?

Vacant property insurance is a specialized policy designed to cover a building that is unoccupied and, in many cases, unfurnished — filling the exact gap a standard landlord policy leaves open during extended vacancies. It restores protection for perils like fire, vandalism, liability, and often water damage that the vacancy clause would otherwise limit.

These policies are built for real-world situations: a rental undergoing major renovation, a property waiting to be sold or leased, an inherited home sitting empty, or a unit between long-term tenants. Coverage can typically be written for a set term — three, six, or twelve months — and adjusted or canceled as the property's status changes, so an owner is not locked into a full-year policy for a two-month gap. Liability protection matters here too — an empty property still attracts trespassers and creates injury exposure, and vacant property policies can respond to those claims.

Disclosure is part of the equation as well: if a property is vacant and the insurer is not told, a later claim can be denied on the grounds that the vacancy was misrepresented, even under an otherwise valid policy. Being upfront about a unit's occupancy status is what keeps the coverage enforceable when you need it. Owners with multiple properties sometimes coordinate vacant coverage alongside their broader portfolio, including any commercial property insurance on larger buildings. Because forms and endorsements differ by insurer, an independent broker can help match the right solution to how long and why the property will be vacant.

Frequently Asked Questions

Why is a vacant rental considered higher risk? Empty buildings carry more risk because problems go unnoticed and unaddressed. There is no tenant to report a small roof leak before it becomes major water damage, to deter break-ins, or to notice a heating failure that leads to frozen pipes. Vacant properties also attract vandalism and squatters. Insurers price and restrict coverage accordingly, which is why the vacancy clause exists in standard landlord policies in the first place.

Does a vacancy clause apply if the unit is furnished but empty? It can, because most vacancy provisions turn on occupancy, not furnishings. A unit with furniture still in it may be considered "unoccupied" if no one is living there, and some policies distinguish between "vacant" and "unoccupied" with different rules for each. The definitions are policy-specific and easy to misread, so confirm exactly how your policy defines the terms before relying on continued coverage.

How do I keep coverage during a renovation between tenants? Tell your insurance broker before the renovation starts. Depending on the scope and timeline, the right tool may be a vacancy permit endorsement on your existing landlord policy, a builder's risk policy for the construction work, or a vacant property policy for a longer gap. Arranging this in advance avoids the coverage suspension that can otherwise take effect once the unit passes the policy's vacancy threshold.

Is vacant property insurance more expensive than standard landlord insurance? Vacant property coverage often costs more than a standard landlord policy because the underlying risk is higher, but the difference is minor compared with an uninsured loss on an empty building. Pricing depends on the property's condition, location, length of expected vacancy, and coverage limits. An independent broker can compare markets to find competitive terms for the specific vacancy situation you are facing.

Protect Your Rental Between Tenants with the Right Coverage

Are you facing a vacancy, a renovation, or a gap between tenants? Contact American Insuring Group to make sure your rental stays protected when it matters most. As independent brokers, we shop the market to find competitively priced landlord and vacant property coverage matched to your situation.

Call American Insuring Group today at (610) 775-3848 or contact American Insuring Group online. Coverage terms vary by policy and state — let us help you close the gap before it costs you.

Tags: Landlord Insurance, Commercial Insurance, commercial property insurance

Handling Insurance in Lease Agreements

Posted by David Ross on Sat, Jul 11, 2026

Contact us for landlord insurance in Philadelphia, Pittsburgh, Erie, Canonsburg, West Mifflin, Lancaster, Lebanon, and throughout Pennsylvania.

Lease agreements do far more than set the rent and the term. They allocate responsibility for everything that can go wrong on a rental property — and insurance clauses are where much of that allocation actually happens. A lease with clear, well-drafted insurance terms protects both landlord and tenant from disputes about who pays when property is damaged, when someone is injured, or when a covered event interrupts the use of the property. A lease with vague or missing insurance language leaves both parties exposed and creates the conditions for expensive disagreements when claims arise. The right landlord insurance program works in tandem with the lease — not in spite of it.

Clarity in Lease Terms — What the Insurance Clauses Should Say

The insurance section of a residential or commercial lease should answer several specific questions clearly. Who is required to carry insurance? What types and amounts of coverage are required? Who is the additional insured on those policies, if anyone? What happens if a party fails to maintain required coverage? And how is the responsibility for the deductible allocated when both landlord and tenant policies might respond to the same loss? Vague references to 'adequate insurance' or 'reasonable coverage' do not answer these questions and create the very ambiguity that leads to disputes.

Specific dollar limits, named coverage types (general liability, property, business interruption, etc.), and clear procedures for proof of coverage create a lease that actually works. Most well-drafted leases also include a waiver of subrogation provision — a clause that prevents either party's insurer from pursuing the other party for losses that the first party's insurance has already paid. This single provision can prevent significant friction between landlord, tenant, and their respective insurance carriers when a claim is handled.

Required Insurance for Tenants

Residential leases commonly require tenants to carry renters insurance that includes both personal property coverage for their belongings and personal liability coverage for injuries to others or damage to the landlord's property. Typical liability limits required in residential leases range from $100,000 to $300,000, with some landlords requiring higher amounts in upscale markets. Requiring tenants to name the landlord as an additional insured on the liability portion of their renters policy is an increasingly common practice that adds meaningful protection at minimal cost to the tenant.

Commercial leases generally require more substantial coverage. Tenants typically must carry commercial general liability, property insurance on their own improvements and contents, workers compensation if they have employees, and in many cases business interruption insurance. Limits depend on the size of the premises, the nature of the tenant's business, and the landlord's risk tolerance. Commercial leases should also require the tenant to provide a certificate of insurance before move-in, and on each renewal of coverage, naming the landlord as additional insured.

Landlord's Policy Implications

From the landlord's side, the lease's insurance clauses interact directly with the landlord's own insurance program. A landlord policy generally covers the structure, certain landlord-owned contents, loss of rental income, and landlord-side liability — but it typically does not cover the tenant's belongings, the tenant's business operations, or liability arising from the tenant's activities. The lease's tenant-insurance requirements are how the landlord ensures that those gaps are covered by the tenant, not absorbed by the landlord's policy.

Landlords should also pay attention to how their own coverage responds in scenarios where tenant insurance is also in place. Issues such as which policy is primary, how subrogation rights are handled, and what happens when both policies might cover a loss are addressed in the underlying policy language and should be coordinated with the lease terms. An insurance broker who reviews lease language alongside the landlord's coverage can identify mismatches before they become claim disputes. Properly aligned, the lease and the landlord policy work together to protect the property, the rental income, and the relationship between landlord and tenant when something goes wrong.

Protect Your Rental Property with the Right Landlord Insurance

Are you looking for a competitive price on landlord insurance that aligns with your lease structure? Contact our team today. As independent brokers, we shop the market to find you the best deal on quality landlord insurance.

Call American Insuring Group today at (610) 775-3848 or contact us online to start saving.


Tags: Landlord Insurance, lease agreements

Insurance for Appliances and Furnishings

Posted by David Ross on Thu, Jun 11, 2026

Insurance-for-Appliances-and-Furnishings-1000

If you are a landlord or tenant, you will want to protect the contents of your rental property. As far as landlord insurance goes, the structure is your biggest concern, but appliances and furniture are significant investments as well. You need to know how insurance will cover these things and help you avoid any unexpected costs if anything is damaged or lost.

Coverage Options

Most homeowners and renters insurance policies include personal property coverage for appliances and furnishings, such as refrigerators, washers, sofas, and dining sets. Generally, these items are safeguarded against standard hazards such as fire, theft, vandalism, and some forms of water damage.

Coverage usually is either actual cash value (ACV) or replacement cost. ACV factors in depreciation, so you’ll get the current value of the item when it’s lost. Replacement cost coverage, on the other hand, reimburses you for the cost to replace the item with a new one of comparable kind and quality without taking depreciation into account.

Look at the limits on your policy. Any high-value items or appliances could exceed the standard coverage limits. In those cases, you should consider additional endorsements or riders to cover them. Having an up-to-date home inventory, along with receipts and photographs, will make a big difference when filing a claim.

Insurance for Furnished Rentals

Landlords who rent out furnished apartments and homes should know that their standard property insurance may not fully cover those contents. In these cases, a landlord insurance policy with contents coverage is a must. This protects items such as beds, couches, and kitchen appliances from damage caused by covered perils.

Tenants who are renting furnished units should also consider renters' insurance. While the landlord’s policy might cover the furnishings themselves, it usually won’t cover the tenant’s personal property or liability. Renters insurance can fill that gap. It protects their belongings and provides liability coverage if the landlord's property is damaged as well.

The insurance policy should clearly define who is responsible for damage to furniture and appliances. This prevents fighting and clarifies each side’s responsibilities.

Handling Claims

As soon as you suffer any loss or damage, inform your insurance company and give them full details. Photos, receipts, and a list of the damaged items may be useful for your claim.

The insurance company will then determine if a claims adjuster needs to review the damage or ask for additional documents. Be prepared to provide the age, condition, and value of damaged items, including model numbers and purchase dates.

Once you have the go-ahead, the reimbursement will be paid out based on your coverage type: ACV or replacement cost. Sometimes, insurers may pay out the depreciated value initially and then release additional funds once the item has been replaced.

Knowing what you have covered and keeping accurate records can make all the difference in protecting your appliances and furnishings. And the right insurance coverage will minimize your financial setbacks and keep your house or rental property running.

Protect Your Rental’s Appliance and Furnishings with Landlord Insurance

Are you looking for a competitive price on landlord insurance? Contact our team today! As independent brokers, we will shop the market to find you the best deal on quality landlord insurance!

Call American Insuring Group today at (610) 775-3848 or contact us online to start saving.

Tags: Landlord Insurance, appliance insurance

Tenant Insurance vs. Landlord Insurance

Posted by David Ross on Sat, Apr 25, 2026

Call us for landlord insurance Philadelphia, Pittsburgh, Erie, Harrisburg, Allentown, Reading, and throughout PABefore landlords rent their property, they and their tenants should understand the difference between tenant insurance and landlord insurance. Although they may sound similar, these coverages have very different purposes. Knowing how they complement each other could help landlords to protect their investment and tenants to protect their belongings.
Differences in Coverage

Renters insurance, also called tenant insurance, is meant to protect the tenant, not the property itself. It usually covers personal items such as furniture, electronics, clothing, and other valuables in case of fire, theft, or water damage. It usually also covers liability if someone gets hurt in the rental unit.

Landlord insurance, on the other hand, is focused on protecting the property owner. This policy usually covers the building's physical structure, including walls, roof, and permanently installed fixtures. It might also cover lost rental income if the property becomes unlivable because of a covered event, as well as liability protection for the property itself.

A key difference is that landlord insurance doesn't cover the tenant's personal belongings. Tenant insurance also doesn't cover damage to the building itself. To ensure you're fully protected on all sides, you need both policies.

Encouraging Tenants to Insure

Many landlords strongly encourage—or even require—tenants to carry renters insurance. This coverage benefits the tenant and the landlord and reduces the chance of future disagreements. For example, if a fire damages a tenant's personal property, the insurance prevents the tenant from asking the landlord to pay for these damages.

Requiring tenant insurance as part of the lease agreement is straightforward. It sets clear expectations for both the landlord and the tenant right from the start. Some landlords even mandate proof of insurance before a new tenant can move in. Others prefer to get updates now and then to ensure coverage remains good.

From a tenant’s perspective, renters insurance is relatively affordable and provides significant peace of mind. Highlighting its low cost and broad protection can make it easier to encourage compliance.

Landlord’s Peace of Mind

Most landlords understand that the right insurance coverage means managing various risks rather than merely protecting their building. Rental properties come with unique risks, including tenant damage and liability claims. Landlord insurance protects against these risks and provides economic security.

Landlords enjoy added protection when their tenants carry their own insurance. This approach, a bit like a safety net, helps fill potential coverage gaps. The result? Fewer costly disputes and less likelihood of unforeseen expenses.

Tenant and landlord insurance are not the same, but they complement one another. Each of them is important, and they protect the landlord's investment while establishing a safer, more professional rental environment for everyone.

Get Total Protection with Tenant and Landlord Insurance

Get the best rates on tenant and landlord insurance. Contact our team today! As independent brokers, we will shop the market to find you the best deal on either type of insurance!

Call American Insuring Group today at (610) 775-3848 or contact us online to start saving.

Tags: Landlord Insurance, Tennant Insurance

Landlord Insurance for Building Exteriors

Posted by David Ross on Sat, Mar 28, 2026

Call us for landlord insurance in Philadelphia, Pittsburgh, Harrisburg, Allentown, Reading, Lancaster, and throughout PAWhen you own rental property, you must protect more than just the interior. The roof, siding, windows, balconies, and the structural facade of a building are always exposed to the weather, accidents, and environmental wear and tear. Damage to a building's exterior can quickly become expensive for landlords and inconvenient for tenants. Having the right landlord insurance helps ensure repairs or replacements can be done quickly without putting undue stress on your finances.
Coverage for Exteriors

Most landlord or rental property insurance policies include protection for the building’s physical structure, often referred to as dwelling coverage. This portion of the policy typically extends to exterior elements such as roofs, exterior walls, siding, windows, doors, gutters, decks, balconies, and sometimes detached structures like garages or sheds.

Exterior coverage is designed to protect against common risks, including storms, wind, hail, fire, falling trees, and certain types of vandalism. If a severe storm damages the roof or high winds tear off siding panels, the policy may help cover the cost of repairs or full replacement, depending on the policy limits and deductibles.

However, it’s important for landlords to verify exactly what their policy includes. Some exterior features—such as fencing, signage, or landscaping—may fall under separate coverage categories or have lower limits. Reviewing the policy details ensures you understand which parts of the building envelope are fully protected.

Specific Conditions

Landlords usually have to meet specific requirements for their insurance policies to cover the exterior of their buildings. Proper maintenance is one of the most common things required. Property owners should keep their roofs, siding, and structural parts in good shape, according to insurance companies. Damage caused by neglect, long-term deterioration, or lack of maintenance is often not covered.

Another condition is the difference between replacement cost and actual cash value. Some policies cover the cost of replacing damaged exterior materials with new ones, while others account for depreciation. For instance, if a storm damages an old roof, an actual cash value policy may pay less because the roof was already close to the end of its life.

Also, most standard landlord policies don't cover certain types of weather events, like flooding or earthquakes. These risks usually require a separate policy. Landlords in areas likely to experience hurricanes, floods, or severe winter storms should carefully review their insurance options to ensure the building's exterior is well protected.

Claims for Exterior Damage

When you have damage to your home's exterior, taking pictures immediately can expedite the claims process. In addition to the photos, write down the date and cause of the incident, and get quotes from contractors for the repairs. Also, inform your insurance company promptly since many policies have a deadline for filing claims.

After you file the claim, a claims adjuster will look at the property to assess the extent of the damage and determine a payout figure. Once the request is approved, the money can be used to repair or replace damaged exterior parts.

Keeping accurate records of repairs, maintenance, and inspections can also help your case. Landlords can avoid expensive problems with exterior damage from storms, accidents, or other unexpected events by keeping up with maintenance and having the right insurance.

Protect Your Rental Property's Exterior with Landlord Insurance

Are you looking for an excellent price on landlord insurance? Contact our team today! As independent brokers, we will shop the market to find you the best deal on quality landlord insurance!

Call American Insuring Group today at (610) 775-3848 or contact us online to start saving!

Tags: Landlord Insurance

Claims Process for Landlords

Posted by David Ross on Sat, Jan 24, 2026

Call us for Landlord Insurance in Philadelphia, Pittsburgh, Erie, Harrisburg, Allentown, Reading, Lancaster, and anywhere in PA

Filing a landlord insurance claim can feel overwhelming, especially when you’re managing tenants, maintenance issues, and the day-to-day responsibilities of owning rental property. However, understanding the claims process for landlords can make the experience far less stressful and help you recover faster after a loss. Whether the issue is property damage, loss of rental income, or liability claims, a straightforward, organized procedure assures fewer delays and better outcomes.

Steps in Filing a Claim

Taking care of any safety issues right away is the first step in filing a claim. Protect the property, stop any further damage if you can, and call emergency services if needed. As soon as you can, call your insurance company once the situation is under control. Most insurance companies have deadlines for filing claims, and waiting too long can make the process more difficult.

When you tell your insurance company about a claim, they will give you a claim number and, in most cases, a claims adjuster. The adjuster will review the details, inspect the property if necessary, and determine whether your policy covers the loss. Be ready to talk about what caused the damage, when it happened, and how it has affected the property or rental income.

After the evaluation, the insurance company will explain the following steps, such as how long it will take to receive payment, how long it will take to have repairs approved, and how to get more information.

Documentation Needed

One of the most important things for a successful landlord insurance claim is having accurate records. Before you start fixing anything, take clear pictures and videos of all the damage. Use wide shots to show the whole picture and close-ups to show the details.

You will also need written records like these:

  • Police reports or incident reports (if applicable)
  • Estimates or invoices from licensed contractors for repairs
  • Records showing that the property was well cared for
  • Lease agreements to back up loss-of-rent claims

Keep a record of all your conversations with tenants, contractors, and the insurance company. Organized records reduce the likelihood of disagreements and speed up the approval of claims.

Streamlining Claims

Landlords can streamline the claims process by being proactive. Review your insurance policy yearly so you comprehend coverage limits, deductibles, and exclusions before a claim ever occurs. Using digital tools to store photos, receipts, and upkeep logs can save valuable time when documentation is necessary quickly.

Working with reputable contractors who provide comprehensive estimates and timelines also helps insurers process claims faster. Finally, preserving open and prompt communication with your claims adjuster reduces misunderstandings and keeps the process moving forward.

By gaining insight into the claims process and preparing in advance, landlords can reduce inactivity, protect their investment, and return their rental property to normal operations as efficiently as possible.

Protect Yourself with Affordable Landlord Insurance

Are you looking for an excellent price on landlord insurance? Contact our team today! As independent brokers, we will shop the market to find you the best deal on quality landlord insurance!

Call American Insuring Group today at (610) 775-3848 or contact us online to start saving.

Tags: Landlord Insurance, Commercial Insurance, Business Insurance

Short-Term Rental Insurance for Landlords

Posted by David Ross on Tue, Dec 30, 2025

Contact us for rental insurance in Philadelphia, Pittsburgh, Erie, Harrisburg, Reading, Allentown, Lancaster, and throughout PA

People may now travel and gain extra money in new ways thanks to short-term rentals. If you let visitors stay in your downtown condo or your cottage by the lake, you take on new risks that regular home insurance might not cover. That's when you should consider short-term rental insurance. This kind of insurance protects hosts from losing money when guests stay too long, damage their property, file liability claims, or have business interruptions that come out of nowhere.

As the market for short-term rentals grows, so does the need for landlord insurance that fits the unique needs of hosting. Property owners may protect their investment and maintain peace of mind by knowing what these insurance policies cover.

Airbnb and Other Platforms

Thanks to services like Airbnb, Vrbo, and Booking.com, hosts may now generate money in innovative ways. But each site has its own approach to keeping hosts safe. For example, Airbnb's AirCover package comes with Host Damage Protection and Host Liability Insurance. This could be a good backup plan, but it's not the same as having short-term rental insurance. Most platform protections have limits, exclusions, and claim thresholds, so owners don't get full coverage.

Vrbo and other sites offer their own types of host liability coverage, but these schemes only protect the site, not the individual hosts. You are always covered, no matter which booking site you use, if you have specialized short-term rental insurance. This includes direct bookings made outside apps developed by other companies.

Specific Policy Requirements

Some insurance companies offer short-term rental insurance policies, but most include basic coverage that rental operators need. At the very least, hosts should look for:

  • Property coverage: Protection for the rental unit and its contents against accidental damage, fire, water damage, theft, and vandalism.

  • Commercial liability: Since hosting is considered a business activity, liability coverage should apply to guest injuries, accidents on the property, or claims of negligence.

  • Business income protection: If a covered event—such as a fire or major repair—makes the rental temporarily unusable, business income coverage can reimburse lost revenue during downtime.

  • Home-sharing endorsements: Some insurance companies require an endorsement to be added to a standard homeowners or landlord policy, while others offer short-term rental policies on their own. It's essential to ensure the policy aligns with how often the property is rented and whether you live there.

Guest-Related Damages

Even the most respectful guests can accidentally damage property. Spilled wine on the carpet, broken furniture, missing items, and clogged plumbing are common issues for hosts. More serious incidents—such as intentional damage, unauthorized parties, or theft—may require filing an insurance claim. Comprehensive short-term rental insurance helps cover repairs or replacements while reducing out-of-pocket costs.

When guests get hurt, it's also essential to protect yourself from liability. You could have to pay a lot for medical care and legal fees if someone slips on icy steps or falls because the floor is loose. Insurance protects hosts from claims that could cost them a lot of money. This makes short-term rental businesses safer and more stable for everyone.

Protect Yourself and Your Property with Landlord Insurance

Are you looking for an excellent price on landlord insurance, including short-terms rentals? Contact our team today! As independent brokers, we will shop the market to find you the best deal on quality landlord insurance!

Call American Insuring Group today at (610) 775-3848 or contact us online to start saving.

Tags: Landlord Insurance, Rental Property Insurance