Insurance Savings and News You Can Use
Join the Conversation!

Umbrella Insurance: Get Protection for Your Income & Assets

Posted by David Ross on Thu, Jan 10, 2013

Do you need umbrella liability insurance? Tips for individuals and business owners in Reading PA, Berks County, Allentown, Pittsburgh, Erie, Harrisburg, Lancaster, Lebanon, York, Hershey, Philadelphia, and beyond.Are You at Risk?

Even if you have good automobile and homeowner’s insurance, you may be liable for excessive damages resulting from a major lawsuit.  Consider what would happen if you were to injure a doctor, lawyer, or other highly paid professional in a car or other accident that prevented him from earning his regular income for the rest of his life. A court could easily award damages far exceeding the limits of your auto, watercraft, or homeowner’s insurance policy. Such damages could drastically alter your lifestyle for many years to come.

That’s where umbrella liability insurance comes in.  The right policy will provide the additional protection needed to withstand such an event. 

You May be at Higher Risk for a Lawsuit

Higher-income individuals who cause an accident have a far greater risk of being sued as lawyers seek out those with deep pockets. In such cases an umbrella policy may provide the protection that could be the difference between maintaining your lifestyle vs. paying punitive damages out of pocket for the rest of your life.

An Umbrella Liability Policy May be More Affordable Than You Think

Umbrella liability insurance tends to be more affordable than other types of insurance because it comes into play only after your other insurance has been exhausted.  For example, a $1,000,000 umbrella policy would cover up to an additional $600,000 of protection on a homeowner’s policy with $400,000 of coverage. The same principle applies to automobile and watercraft insurance. Increased savings may be found by purchasing your umbrella policy from the same insurance provider as for your home, car, commercial property, or watercraft.

Commercial Property and Umbrella Insurance

Are you a business owner or landlord? If so, you are at greater risk of incurring a lawsuit. Landlord insurance in the form of an umbrella liability policy can provide additional protection against lawsuits from tenants, as well as from being sued for slander or libel by disgruntled employees.

Do You Have an Adequate Umbrella Policy?

If you would like help in obtaining the right level of insurance protection then please click to contact us, or call us at 800-947-1270.
Affordable umbrella liability insurance for Reading PA, Berks County, Philadelphia, Allentown, Harrisburg, Lancaster, Lebanon, York, Pittsburgh, Erie, Pennsylvania and beyond.

Tags: Umbrella Liability Insurance, Homeowners Insurance Lancaster Pa, Homeowners Insurance Philadelphia Pa, Small Business Insurance, Small Business Insurance Reading PA, Landlord Insurance, Car Insurance, Homeowners Insurance, Homeowners Insurance Allentown Pa, Homeowners Insurance Reading Pa, Homeowners Insurance Harrisburg PA, Homeowners Insurance York PA, Umbrella Insurance, Commercial Insurance, Business Insurance

What is Landlord Insurance and Do You Need It?

Posted by David Ross on Fri, Jan 04, 2013

Landlord insurance tips for Berks County, Reading PA, Philadelphia, Lancaster, Lebanon, York, Harrisburg, Pittsburgh, Erie, Allentown, Bethlehem, State College, PA and beyond. Landlord Insurance Basics

Landlord insurance is designed to protect the landlord from incurring losses on his or her rental properties. This ranges from property damage to court/legal costs and more, including loss of rental income from a property that becomes inhabitable due to storm damage or other causes.

Do You Need Landlord Insurance?

Does life throw unexpected circumstances our way? If you are a landlord, then of course you need landlord insurance. The question is not whether you need it, but what types of coverage and how much of each type you need.  For example, with lawsuits rampant in today’s society, it is wise to consider coverage for discrimination and slander, even if you are certain that you would never commit either. To sleep better at night you may even want to consider comprehensive coverage, which protects you against circumstances not specifically identified in your policy.

Your Property is a Major Investment. Treat it as Such.

Would you go without homeowners insurance or car insurance? Then why consider going without landlord insurance? Your rental property value may easily eclipse your home value, and a loss of your rental property due to fire, storm damage, or other factors can lead to a long-lasting financial upheaval and loss of cash flow that can be easily avoided with the proper insurance coverage.

Not All Landlord Insurance is Created Equal

It is important for landlords to understand exactly what is and what is not covered under their policy. Policies may vary widely, so be sure to work with your insurance agent to understand all the important aspects of your current coverage and to uncover your potential vulnerabilities. For example, your policy may cover only certain types of damage, such as exterior vs. interior damage.  Likewise, legal costs may be excluded from your policy. Be sure to ask your independent insurance agent what types of additional coverage are available from your current carrier and from competing insurance carriers, and then consider switching carriers or upgrading your policy if needed.  Your independent insurance agent represents multiple insurance companies, so changing to another carrier is easy with the right agent.

Need Help Understanding Your Landlord Insurance Options?

Contact us today for a free evaluation: 800-947-1270

Learn more about landlord insurance. Serving Berks County, Reading PA, Philadelphia, Pittsburgh, Allentown, York, Harrisburg, Lancaster, Lebanon, State College, Pennsylvania and beyond.

Tags: Business Insurance Berks, Small Business Insurance, Small Business Insurance Reading PA, Commercial Insurance Allentown PA, Commercial Insurance Lancaster PA, Commercial Insurance Harrisburg PA, Landlord Insurance, Insurance Reading Pa, Landlord Insurance Reading PA, Landlord Insurance Berks County, Commercial Insurance, Commercial Insurance Reading PA, Business Insurance, Commercial Insurance Philadelphia PA, Commercial Insurance York PA, commercial property insurance, Commercial Insurance Berks County

5 Ways to Save on Landlord Insurance

Posted by David Ross on Tue, Dec 18, 2012

As a landlord, obtaining the right level of public liability insurance coverage is important for your peace of mind and your bottom line, especially when you experience a large claim against your landlord insurance.

Tips to save on landlord insurance, public liability insurance. Berks County, Reading PA, Philadelphia, Harrisburg, Pittsburgh, Allentown, Erie, Lebanon, York, Pennsylvania.5 Easy Steps to Better Public Liability Insurance Protection & Greater Savings:
#1.  Place All Your Properties on One Landlord Insurance Policy (Public Liability Insurance Policy)

It is possible to save a considerable sum by combining all your properties under the same insurance provider.  Rather than insuring each property separately, ensure them all under a single policy with a common renewal date. As a bonus, your bookkeeping will be simplified as well.

You can also phase your properties into a common Landlord Insurance policy over time by moving each to the combined commercial property insurance policy as the renewal date for each individual policy comes due.  As you purchase new properties, be sure to add them to the combined policy for even greater savings.  Depending on the insurer, you may be able to group more than one type of commercial property under the same policy, such as apartments vs. shops.

#2. Seek Professionals as Occupants

Consider gearing your marketing efforts to appeal to professional occupants with full time employment.  Some insurers charge a higher premium for landlords of college students and others who statistically are more likely to cause property damage. By seeking occupants who are full-time professionals, you are appealing to a low-risk group with correspondingly lower landlord insurance costs.

#3. Insure Your Properties for the Right Amount

Property values and replacement costs are constantly in flux. Therefore, check the amount of coverage on each property periodically to be sure that it accurately reflects your true replacement cost.  If you are over-insured then your premiums will be higher than they would be for the right amount of coverage. On the other hand, if you are under-insured then you risk incurring major and lasting financial problems if your property is destroyed and you lack sufficient insurance protection to rebuild it properly.

#4. Add a Larger Deductible to Your Landlord Insurance Policy

By adding a larger deductible to your policy, your premiums may drop significantly. This approach amounts to self-insuring for the deductible amount. Follow these steps to determine if paying a higher deductible is likely to be a better deal:

  1. Find out the annual premium cost to insure your properties with your current deductible amount vs. the cost with a higher deductible.
  2. Multiply the annual savings by 5 years (or whatever period you are likely to keep the property) to estimate your total savings on landlord insurance premiums over a 5-year period.
  3. Determine how many claims you would have to incur over 5 years before your savings on premiums would be consumed. If that number of claims looks unrealistically high, then it may make sense to increase your deductible and pocket the savings in premiums.

#5. Add a Security System to Your Commercial Properties

This is one of the most often-overlooked ways to save. Even a simple burglar alarm may save a meaningful amount on your insurance, possibly 10%. Compare the 5-year savings to the cost of the system. Chances are good that you may be money ahead by adding the system, and you and your tenants will have greater peace of mind as well.  An independent insurance agent who represents multiple companies provides the best opportunity to save by comparing quotes from competing insurers. 

Get Help

Do need help in finding the right landlord insurance for your commercial property? Contact us today for a free, no-obligation consultation on ways you can save more while enjoying better public liability insurance protection.

Save on public liability landlord insurance. Serving Reading, PA, Berks County, Philadelphia, Lancaster, Lebanon, York, Harrisburg, Allentown, Bethlehem, Pittsburgh, Pennsylvania, and beyond.

Tags: Public Liability Insurance, Business Insurance Berks, Small Business Insurance, Small Business Insurance Reading PA, Commercial Insurance Allentown PA, Commercial Insurance Lancaster PA, Commercial Insurance Harrisburg PA, Landlord Insurance, Public Liability Insurance Reading PA, Public Liability Insurance Berks County, Landlord Insurance Reading PA, Landlord Insurance Berks County, Commercial Insurance, Commercial Insurance Reading PA, Business Insurance, Commercial Insurance Philadelphia PA, Commercial Insurance York PA, commercial property insurance, Commercial Insurance Berks County

Life Insurance: 7 Ways to Cut Costs

Posted by David Ross on Sat, Dec 15, 2012

Although we'll all die someday, when we do, we don't want to leave our loved ones with huge debts or financial problems. To ensure your family is financially secure in case you should pass away unexpectedly, you need life insurance. Like other financial products, it is important to get an insurance solution that provides the best value for your money.

Smart ways to reduce your life insurance costs. Serving Reading, PA, Berks County, Allentown, Philadelphia, Lancaster, Lebanon, York, Harrisburg, Pittsburgh, State College, Pennsylvania and beyond.An affordable policy can help you save money without straining your budget. Here are seven tips to help you pay less for insurance:
1. Determine the amount of life insurance you need

Check your finances and determine how much life insurance you need. Consider the expenses that your spouse and loved ones will have to bear should you pass away unexpectedly. Think about short-term expenses such as funeral expenses, buying food and paying rent, as well as long-term expenses such as college education costs.

Check the amount of savings you have and use life insurance to cover the difference between the savings and the total expected expenses of your loved ones.

2. Decide on the type of life insurance to apply for

You can apply for permanent or term life insurance. Permanent insurance offers protection for your whole life while term life insurance provides protection for a specified term. Term insurance will help you save on your payment cost. The insurance is cheaper than permanent insurance and is the better option in many situations. However, in some cases a whole life policy may work best for you, depending on your investment portfolio and strategy.

3. Shop around for the best rates

Insurance providers charge different rates. To get the best deal in the market, shop around and compare the offers of different providers. Look at both the cost of premiums you will pay and the coverage provided by each insurer. Use online insurance comparison websites to compare rates from different providers, but be sure to speak with a knowledgeable insurance agent before making a final decision. Remember, and independent agent is positioned to save you money because he or she represents many different insurers, and can select the best policy for your specific needs.

4. Check for hidden fees

As you shop around, be sure to understand all hidden fees. Some insurance companies charge fees every month instead of annually. Some policies also come with riders, or add-ons, that may not benefit you at all. Examples of add-ons that you should understand in terms of both cost and benefits before reaching a decision include:

  • Accident death benefit
  • Waiver of premium rider
  • Disability income rider
  • Accelerate death benefit

5. Make lifestyle changes

Staying healthy can significantly lower your insurance premiums. People with lifestyle diseases such as obesity and diabetes usually pay higher premiums. Before you apply for insurance, think about getting into shape, quitting smoking, and reducing alcohol consumption. If you already have purchased life insurance, you can renegotiate the payments when you start leading a healthier lifestyle.

6. Round up your payments

Most of the time, you will pay less for coverage that is rounded up into larger multiples. For example, a $500,000 policy may cost less than a $400,000 policy. Check with your insurance provider for the rate per $1000 of coverage, which usually goes down when a certain amount of coverage is achieved. The figure will help you determine the amount of benefits you will receive for the least amount of money.

7. Find an independent life insurance agent and the right insurance company

Some companies offer competitive rates for conditions such as cancer, heart disease and diabetes. These companies have underwriters who analyze the condition of insurance buyers on a case-by-case basis rather than setting a lump sum for buyers with a particular condition in one group. For example, if you have mild diabetes, you are likely to pay less than a person with chronic diabetes. An independent agent can help you compare such options from several companies, resulting in a better match between your needs and your policy.

Need help finding the right life insurance at the right price?

We can help. Contact us at 800-947-1270.


Learn more about how to save on life insurance in Pennsylvania and beyond

Tags: Life Insurance Berks Pa, Life Insurance Philadelphia Pa, Life Insurance Lancaster Pa, Insurance Reading Pa, Life Insurance Reading PA, Life Insurance Allentown Pa, Life Insurance Harrisburg Pa, Life Insurance York Pa, Life Insurance

Retirement Planning a Key Reason for Life Insurance

Posted by David Ross on Tue, Dec 11, 2012

Life Insurance - It's "Booming"!

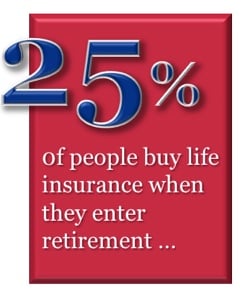
Life Insurance for Retirement b 250With the large baby boom generation entering retirement age, retirement planning is getting more and more attention. Interestingly, while marriage is still the leading cause for people to buy life insurance, retirement is also a major motivation. In fact, research from Northwestern Mutual Life, as conducted by Harris Interactive, shows that 25 percent of people buy life insurance products when they enter retirement -- almost as much as the 32 percent of people that buy it after getting married. 
Income and Retirement

On first glance, this may seem a bit counter intuitive. After all, many people buy insurance when they are younger to protect their spouses and family against a loss of income and Northwestern Mutual's research bears this out. As people age, protecting their incomes from work becomes less important as their living expenses drop and income from their retirement portfolio begins to replace wages. 

Retirement today is more complicated than in the past. Today, many retired people still work, although they may work reduced hours or switch careers. This can create a need to secure income. In fact, many of the retired people that purchase life insurance cite a desire for income security as a major motivating factor. 

Making Money on Life Insurance... Without Having to Die

Purchasing a life policy can do much more than protect income. It can also augment existing income. Products that include an annuity feature provide yearly cash payments that provide retired couples with more money and a more fulfilling lifestyle. Whole life and universal life insurance products can be smart savings vehicles, building value and earning very secure returns while also providing a death benefit like other types of life coverage.

Insuring the Life of a Business

Life insurance coverage is especially valuable as an estate tax planning tool for retired people with businesses or large tangible assets but that also have comparatively small pools of cash, securities or other types of liquid assets. When people in this situation die, their heirs inherit their assets but will have to pay an onerous estate tax on the value of assets transferred to them that exceed any exclusion. Without cash, they would have to sell the asset or business to pay the estate tax liability. To mitigate against this eventuality, some retired asset holder purchase additional life insurance. Upon their passing, the insurance pays a tax-free death benefit which their heirs can use to pay the estate tax, leaving them the ability to retain the assets.

With all of these benefits, it is not surprising that 25 percent of retired couples are purchasing and benefiting from life insurance. As more people discover its benefits, it stands to become even more popular.

Do you need better life insurance coverage?

We can help. Contact us at 800-947-1270 to review your options.

Save on high quality life insurance for your self, family, or business. Serving Reading, PA, Berks County and beyond.

Tags: Insurance Berks Pa, Life Insurance Berks Pa, Life Insurance Philadelphia Pa, Life Insurance Lancaster Pa, Insurance Reading Pa, Life Insurance Reading PA, Life Insurance Allentown Pa, Life Insurance Harrisburg Pa, Life Insurance York Pa, Life Insurance

Health Insurance Pitfalls to Avoid During Open Enrollment

Posted by David Ross on Sat, Dec 01, 2012

Get the Most from Your Employer Health Care Program

Health Insurance Tips - Problems to Avoid During Open EnrollmentWith the end of the year fast approaching, many employees are starting to become anxious. It’s that time of year again, the time when they get to tweak their health insurance benefits. While this may be exciting to some, the responsibility to choose the right health insurance plan can be a source of tension for others.
There are many reasons for this. Personal circumstance comes into play, including additions to family. Since the days when employers offered either a low-cost HMO or an expensive PPO, the maze of health insurance options has increased significantly. With health insurance costs on the rise, it’s more important than ever to make sure you are getting the most coverage for your money. 

Here are 5 mistakes to avoid in an open enrollment benefit session: 

Mistake #1- Saying No to Health Savings Accounts

Less than 20% of those given the option of opening a Health Savings Account choose to take advantage of this potentially valuable opportunity. If you break it down, these turn out to be the equivalent of free money, and can really give you a leg up towards paying for medical expenses. 

Mistake #2- Picking the Cheapest Health Insurance Premium

It’s easy to look at a low cost and choose the cheapest health insurance plan because we may think it's all we can afford. What many fail to realize, however, is that low-cost health insurance premiums often offer significantly less coverage. This could lead to big trouble in the long run if your health care needs outweigh the coverage available. 

Mistake #3- Not Doing Your Health Insurance Research 

Nine out of ten people renew their old health insurance plans for the upcoming year. This isn’t always a bad thing, such as when your needs haven’t changed and you’ve researched the available options. However, even if your health insurance needs are the same as they were last year, review the plans available to make sure that nothing has been changed on their end. Benefits and premiums may not be the same as last year, so make sure that you know exactly what you’re signing up for. 

Mistake #4- Under-Buying

Under-insuring is one of the worst mistakes you can make, as once you’ve signed into a health insurance plan, you’re locked into it either until there is a change in family demographics or open enrollment comes up again. That’s it. There’s no in between. It would be nice to think that by the time you need it, you’ll have thrown enough money into your Health Savings Account to cover the cost of the premium, but there’s no guarantee. You could find yourself paying a large sum out of pocket.

Mistake #5- Over-Buying Health Insurance Coverage 

Throwing a high premium at the possibility of a life altering health-related disaster may provide you with quite a safety net, but financially it could turn out to be an unwise move. This is not to say that choosing the cheapest health insurance plan is always the best option for an individual with a clean bill of health, as we are all at risk for accident or unexpected illness. Finding something in the middle is ofen sufficient. Consider a high deductible with a limited network to keep premium costs low while providing coverage against a major health care expense.

Yes, open enrollment can be a source of tension, but if you play it right, as most people don’t, you’ll find that next year’s open enrollment isn’t the confusing maze that some make it out to be. Open enrollment for health insurance coverage is there to give you options that can help you. Don’t pass up a good opportunity to make a smart move. 

Do you need personal health insurance, or better health insurance for your employees?

We can help. Please contact us today: 800-947-1270

Click to save on high-quality, affordable health insurance in Reading, PA, Berks County, and beyond

Tags: Health Insurance Reading PA, Health Insurance Allentown, Health Insurance Harrisburg, Health Insurance, Health Insurance Berks County, Health Insurance Philadelphia, Health Insurance Lancaster, Business Insurance

Life Insurance Survey: Most Woefully Unprepared [INFOGRAPHIC]

Posted by David Ross on Tue, Nov 20, 2012

Poor excuses for no life insurance. See us for help in buying the right insurance. Reading, PA, Berks County, Philadelphia, Lancaster, Harrisburg, Allentown, Lehigh Valley, and beyond.Life insurance coverage might not be the first thing you think of when considering your financial planning.  However, it is an extremely important component of that planning.  If the unexpected happens, the people you leave behind could be left with the very same financial hardships you’ve been working so hard to prevent, especially if you haven't put the proper life insurance in place.  Sadly, as you'll see from the data below, most people fall into one of two categories: uninsured or underinsured.
Survey: 39% Have No Life Insurance

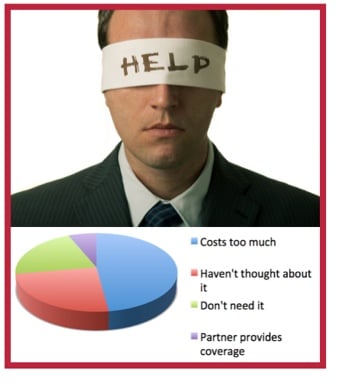
If life insurance hasn’t made it to your priority list, you aren’t alone.  An August 2012 survey from Harris Interactive found that 39% of respondents had no coverage.  Most people thought it would cost them too much, but many hadn’t even considered whether they need it.  In short:

Of the 39% with no coverage:

  • Costs too much:  45%
  • Haven’t thought about it:  23%
  • Don’t think they need it:  20%
  • Partner provides coverage:  6%

61% with Life Insurance are Open to Risk

People who had life insurance coverage had not eliminated their risk, either, though.  How much coverage is needed is based on many variables.  There are the immediate expenses, of course, such as funeral expenses.  Then there are longer-term considerations, such as mortgages, college expenses, and inflation. 

The survey found that 61% of respondents had too little coverage based on a rule of thumb that a million dollar policy would be sufficient to cover a median household income of $50,000.  Most of these respondents hadn’t really considered how much life insurance would be needed to take care of those left behind when all the variables are considered.  

Of the 61% with too little coverage based on their income:

  • $100,000 of coverage or less:  53%
  • $100,000 to $250,000:  20%
  • $250,000 to $1,000,000:  15%
  • $1,000,000 or above:  2%

(You can see an infographic of this data here.)

As you can see, most Americans are woefully unprepared or under-prepared when it comes to life insurance.  But it really doesn’t have to be this way since these policies can be very affordable and flexible. 

To protect the work you’ve done in life, and protect those you leave behind, talk with an insurance adviser about your specific situation.  They can help you consider all the variables and calculate what amount of life insurance you should incorporate into your financial planning.  

Need Help Understanding Your Life Insurance Options?

If you'd like help reviewing your life insurance coverage, please contact us today for a free, no-hassle consultation.  

Contact us to discuss your Life Insurance needs. Serving Berks County, Lancaster County, Lehigh Valley, Montgomery County, Allentown, Philadelphia, Pennsylvania.

Tags: Life Insurance Berks Pa, Life Insurance Philadelphia Pa, Life Insurance Lancaster Pa, Life Insurance Reading PA, Life Insurance Allentown Pa, Life Insurance Harrisburg Pa, Life Insurance York Pa, Life Insurance

4 Ways to Cut Workers Compensation Insurance Costs

Posted by David Ross on Sat, Nov 03, 2012

How to control workers compensation costs. Serving Reading, PA, Berks County, Bucks County, Lancaster, York, Philadelphia, Harrisburg, Allentown, Lehigh Valley, Pittsburgh, Hershey, Harrisburg, Pennsylvania and beyond with workers compensation insurance tips.For most small businesses, workers compensation insurance costs can eat up a fair percentage of their income. While this type of coverage is essential, especially for riskier professions, there are a few ways to minimize your workers comp insurance expenditures without sacrificing the level of coverage necessary for your enterprise.
Here are some helpful tips to keep your costs under control:

Correctly classify your employees

Take a look at what you are paying in workers comp insurance per employee, and then ask yourself if all of these employees require the same level of coverage in relation to the riskiness of their profession. For instance, a typical office manager is far less likely to require workers compensation payments than a typical carpenter. Most workers compensation insurance companies charge different rates for these professions accordingly, so make sure that you aren't being overcharged for workers compensation insurance that you don't need. 

Familiarize yourself with relevant OSHA safety standards, and train your employees accordingly

As they say, an ounce of prevention is worth a pound of cure. OSHA regulations exist for a reason, and one should always be careful about staying within the letter of the law in this matter. If you are unsure of the relevant standards, your local OSHA safety office can offer clarification. Make sure that your employees are well aware of their rights under OSHA statutes, and what they need to do in order to remain compliant. A workforce that is familiar and compliant with the basic safety standards of their industry is one that is less likely to utilize workers compensation insurance over the course of their tenure.

Ensure that all tools, equipment, and grounds are safe/in good working order

Make it a point to periodically check any motorized tools for dirt, debris, or other potential hazards, and have your employees periodically check things like brakes, fluid levels, and other vehicular aspects that can potentially pose a safety hazard if not up to par. Your workers compensation insurance is less likely to be needed if all tools and vehicles are in proper working order, so make sure that your employees understand that it is part of their regular work duties to clean, maintain, and lubricate their tools, vehicles, and work stations alike. You should also make sure that any physical grounds (such as your office, parking lots, and walkways,) are easy to access, free of debris, ice, or snow, and are as safe as possible. Workers compensation insurance will need to be tapped into if someone hurts themselves while on your property, so bear this in mind as you go!

Address claims quickly and compassionately

Whenever the unthinkable happens despite the best laid  plans, you can help to minimize the impact on your workers compensation insurance rates in a number of different ways. Make sure that the employee gets the medical help they need immediately, and make sure that their expenses are paid accordingly. Minimize the need for lawyers to get involved, make it as easy as possible for the employee in question to recover and return to work, and show genuine concern all the way through. This should help keep your workers compensation insurance rates reasonable throughout the life of your business.

In short, make sure that you look over your workers compensation insurance rates closely, itemize what you are paying per employee and why, and take all necessary steps to help your employees realize that their safety is priority number one!

Need help with reducing workers compensation costs? Contact American Insuring Group today to learn more.

Contact us to learn more about reducing your workers compensation insurance costs. Serving Reading, PA, Harrisburg, Philadelphia, Allentown, Lehigh Valley, Lancaster, Lebanon, York, Hershey, Pittsburgh, Erie, State College, Irwin, PA and beyond.

Tags: Workers Compensation Insurance, Business Insurance Berks, Commercial Insurance Allentown PA, Commercial Insurance Lancaster PA, Commercial Insurance Harrisburg PA, PA Workers Compensation Insurance, Commercial Insurance, Commercial Insurance Reading PA, Business Insurance, Commercial Insurance Philadelphia PA, Commercial Insurance York PA, Commercial Insurance Berks County

Homeowners Insurance Tip: PA Residents Won't Pay Hurricane Deductibles on Sandy-Related Claims

Posted by David Ross on Fri, Nov 02, 2012
PA Governor says no deductible for Hurricane Sandy claimsAccording to WFMZ-TV: "Gov. Tom Corbett announced Thursday that Pennsylvania homeowners will not have to pay hurricane deductibles on insurance claimsstemming from damage caused by Hurricane Sandy.

"Insurance deductibles could have added significant costs to Pennsylvanians already struggling to clean up and rebuild after Hurricane Sandy," Corbett said. "Insurance companies have deployed catastrophe teams to Pennsylvania and they have been advised that hurricane deductibles should not be applied to any homeowner's insurance claims.""

For the full article, click here. 

Tags: House Insurance Reading PA, Homeowners Insurance Lancaster Pa, House Insurance Allentown Pa, House Insurance Lancaster Pa, Homeowners Insurance Philadelphia Pa, Insurance Reading Pa, House Insurance, Homeowners Insurance, Homeowners Insurance Allentown Pa, Homeowners Insurance Reading Pa, House Insurance Philadelphia Pa, Homeowners Insurance Harrisburg PA, Homeowners Insurance York PA

Commercial Vehicle Insurance Tips and FAQs

Posted by David Ross on Tue, Oct 30, 2012

When looking for commercial vehicle or van insurance in small to large towns from Reading to Philadelphia and beyond, there are a few points to consider, and some tend to get lost in a potential insurance minefield – here are a few frequently asked questions many ask when searching for the right insurance for their small business.

Is it hard to insure a vehicle for commercial use?

Commercial Vehicle Questions, Answers, and Tips. Serving Reading, PA, Berks County, Allentown, Bethlehem, Harrisburg, Philadelphia, Lancaster, York, Lebanon, Hershey, State College, Erie, Pittsburgh, Pennsylvania and beyond with reliable commercial vehicle insurance.Not really. Anyone can apply to insure a commercial vehicle, (for example, a van), but they will find they are restricted when it comes to personal or private use of that vehicle. As long as the vehicle falls under commercial use, like delivering goods or providing a service (say, if the owner is a builder just using the van to get from A to B) then it is much easier to obtain insurance than if the applicant also wanted the vehicle for private use.
Define ‘commercial vehicle’?

Not sure if your vehicle falls under the right guidelines? Here are the main types of commercial vehicle:

  • Goods-carrying vehicles: this is the most common type of commercial vehicle, used to transport products or necessary items for services. This can range from small cars and vans to larger trucks.
  • Passenger-carrying vehicles: this applies to buses, coaches, and hire cars.
  • Forestry and agricultural vehicles
  • Special construction vehicles: vehicles that serve a particular purpose are known as ‘special types’ of vehicle and apply to ambulances, fork-lift trucks, and cranes.

What about windshield coverage?

Windshield coverage usually comes down to the insurance company and the level of coverage taken out, but this type of coverage is typically available for commercial vehicles as a policy extra, under "Comprehensive" coverage.

How can I lower my van insurance premium?

There are a number of ways that some companies do this, but here are three ways for customers to reduce their premiums:

  • Usage - how the vehicle is used can lower your insurance premiums.  If you park the van at one jobsite for the day will be a lower cost than if you travel to mutiple locations during the day.
  • Safe drive Badge – a simple sticker on the back saying ‘How’s my driving?’ with a number on the back (preferably to the insurance company) will also reduce premiums. This is because anyone driving dangerously will obviously be reported by other drivers, hypothetically making the driver in question more cautious about their driving.
  • Driving Convictions – this is a simple one; don’t acquire any speeding convictions. Insurance companies tend to ramp up the premiums for people who have previous driving convictions. 


Get Help - Get the Right Commercial Vehicle Insurance for Your Car, Van, or Truck

We will be glad to address any further questions you may have. Please contact us, or request a free, no-hassle insurance quote today. We compare prices from several competing, highly reputable insurance providers to make sure you get the right policy at the best price. Whether you are in Philadelphia, Reading, Lancaster, Allentown, Harrisburg, or beyond, we'll find the best value in commercial vehicle insurance for your van, car, or truck. Simply call or click today to get started.
Free commercial insurance quote from American Insuring Group. Serving Reading PA, Berks County, Philadelphia, Lancaster, Lebanon, York, Hershey, Harrisburg, State College, Erie, Pittsburgh, Allentown, Bethlehem, Kutztown, Pennsylvania and beyond with high-quality, affordable business insurance.

Tags: Van Insurance, Commercial Vehicle Insurance, Business Insurance Berks, Small Business Insurance, Small Business Insurance Reading PA, Commercial Insurance Allentown PA, Commercial Insurance Lancaster PA, Commercial Insurance Harrisburg PA, Commercial Insurance, Commercial Insurance Reading PA, Business Insurance, Commercial Insurance Philadelphia PA, Commercial Insurance York PA, commercial property insurance, Commercial Insurance Berks County