It’s a bird. It’s a plane. No, it’s a drone!
 Businesses are discovering many uses for drones – also known as unmanned aircraft systems (UAS). In fact, total spending for military and commercial drones is expected to reach $89.1 billion over the next ten years. This translates into approximately 30,000 small commercial drones in use by 2020, according to the Federal Aviation Administration (FAA).
Commercial Application of Drones: Implications for Commercial Insurance
Drones are already being used by real estate brokers to get images of properties from the air, by farmers to monitor crops, by insurance claims adjusters to view damaged property, by the Forest Services to monitor fires, and by movie companies in film production.
Almost any job that currently requires an aircraft is a good candidate for a drone, since drones are considerably less expensive to operate. Major online retailers are already planning on using drones to deliver packages. Plus, drones can provide safer options and prevent worker injuries in many cases. For example, if you own a construction company and you need the top beams of a building inspected, would you rather send a man several hundred feet off the ground or a drone? The bottom line is that if you are operating drones for business purposes then it's critically important to add drone insurance to your business insurance policy.
Other potential uses for drones include:
- News: aerial reporting
- Insurance: claims and underwriting operations
- Service: table service at restaurants and bars!
Commercial Insurance Implications for Businesses Operating Drones: A Closer Look
This proliferation of drones increases the need to address commercial insurance liability and coverage issues, most notably - personal injury and invasion of privacy. Drones are excluded in about 99 percent of Commercial General Liability policies available today. Legal issues include “trespassing” drones; airspace ownership laws; and the question of federal aviation laws vs. state laws. In addition, many drones have high-powered cameras, infrared sensors, facial recognition technology, and license plate readers, which also brings up concerns regarding invasion of privacy, spying, stalking, and harassment.
Insurance Companies Scrambling to Supply Drone Insurance Coverage
 In February 2012, congress mandated that the Federal Aviation Administration (FAA) find a way to integrate drones into U.S. airspace by September 2015. With that deadline looming, the FAA is nowhere close to finalizing its plans. This lack of regulation and the fact that there is very little loss history available at this point makes it challenging for insurance companies to develop policies. It's therefore likely that drone insurance rates may vary widely among insurance providers. Therefore, it's helpful to acquire drone insurance protection from an indepdent insurance agency who is free to shop around among competing brands of insurance providers in order to help you obtain the proper coverage at a fair price.
Drone Insurance Risk Factors - Similar to Aircraft Insurance Risks
Since drones are regulated by the FAA, many of the same questions that an underwriter looks at with an aircraft will also apply to a drone, such as its function or intent, its takeoff and landing location, whether it will be operating over a populated area, and its flying altitude. However, a drone is not a manned aircraft. Underwriters will need to look at liability, personal injury, and invasion of privacy, property and workers’ compensation when creating insurance policies for commercial drones.
Currently there are about 21 insurance companies that write aircraft product liability policies – up from just nine a few years ago. Someday requesting insurance for drones and drone-related operations will become routine, but for now we’re faced with the challenge of keeping up with the issues that come along with quickly advancing technology.
 For more information about drone insurance and other commercial insurance needs, contact American Insuring Group at (800)947-1270 or (610)775-3848. As an independent insurance agency, we're postitioned to help you save on insurance by shopping your needs among many competing insurance providers. Call today.
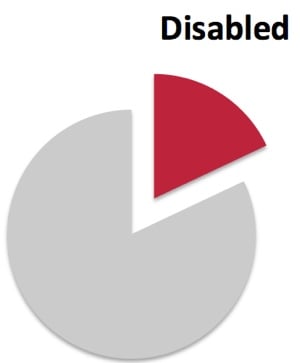 More than 50 million Americans – 18% of the population – have disabilities, making them the largest minority group in the country. In addition, approximately 71.5 million baby boomers will be over the age of 65 by the year 2030; many will require special provisions to meet their age-specific physical needs.
 You say you have good
 The inability to get the right care, from the right provider, at the right time is one of the leading causes of increasing medical costs.
 Contact Us for Workers Compensation Insurance Assistance
 Did you recently get married? Have you started thinking about having children? Are you already pregnant? Congratulations! This is a very exciting time in your life!
 Fraud, waste, and abuse continue to drive up the cost of administering workers’ compensation programs. Workers’ compensation fraud, which accounts for approximately one-quarter of all insurance fraud, comes in all forms: injury while off work, multiple claims, injury concurrent with termination, and many more.
 For additional methods to reduce the cost of workers’ compensation, including getting the best rate on quality workers comp insurance,
 If you own a fleet of vehicles that are used exclusively for your business or you own a freight truck or delivery truck, you probably understand that you need commercial vehicle insurance on those vehicles. But what if you have one vehicle that you use to deliver pizzas? What if you use your personal vehicle to drive to job sites or to meetings?
 Smart business owners know that insurance is important to protect their business and assets. But, knowing which ones are right for your business can be a challenge. No one wants to be caught without the right
 These five business insurance questions are a great starting point for any business owner, but you don’t need to go it alone. The advice of a trusted and experienced independent insurance agent from American Insuring Group can help ensure that you obtain the right insurance at the right price for your business.
 Whether you’re a subcontractor or a general contractor – whether you build small backyard sheds or giant commercial buildings – whether you’re a one-man remodeling business or a multi-million dollar construction company, there are three types of insurance you need to consider. In other words, the size of your business and the size of the project make little difference. If you want to protect your investment, your employees, and even your business, there are three types of
 For more customized information about your construction insurance or
 s there a non-profit organization near and dear to your heart that you would like to assist financially? Maybe it’s a religious organization, a pet shelter, or a children’s home. You aren’t alone. It turns out that we are a very charitable people with more than 95% of American households giving an average of just under $3,000 a year to charity. But, do you ever wish that you could do more? There is a way to give more financial support to your favorite charity.
 To find out more about giving the gift of a life insurance policy to your favorite charity,