Chances are that your current homeowner’s insurance policy is weaker than you think in terms of the financial protection it offers. That’s because many insurers have been steadily changing their coverage to increase deductibles and to add new loopholes protecting the insurance company from excessive loss. To make matters worse, homeowner’s insurance rates have climbed 69% over the past 10 years and now average approximately $1,000 per year.
 Why the Big Homeowner’s Insurance Cost Increases?
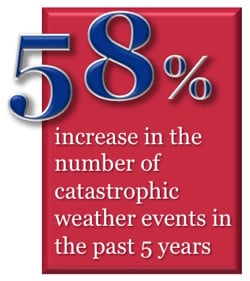
So why are insurers raising home insurance rates, cutting coverage, and increasing deductibles in Reading, Philadelphia, Allentown, Lancaster, and all across Pennsylvania and the US? Is it nothing more than unbridled greed? Hardly. Insurers are experiencing factors beyond their control that are driving up costs. The biggest factor alone, the weather, has resulted in a 58% increase in the number of catastrophic weather events in the past five years vs. the prior five, climbing from 602 to 953 according to insurance industry data. Of course, along with each disaster comes a series of insurance industry payouts to policy holders.
Another factor driving these changes is that states have denied insurers’ requests to increase their rates to the full extent needed to capture the true increases in weather-related payouts. As a result, insurers have resorted to shifting a much larger percentage of the cost of homeowner’s claims to their customers in an effort to remain solvent, and this has been done by cutting coverage. Many homeowners are on the hook for far more of the cost of repairs than they were five years ago. Homeowner’s insurance is among the least profitable forms of insurance, and, as they say, you can’t get blood from a rock, so something has to give, and that has been both the extent and cost of coverage.
Get Help: Homeowner’s Insurance Coverage Varies Widely
 Because house insurance coverage varies widely among insurers, and given that the specifics of what is covered and what is not are often buried in the insurance policy fine print, it is wise to seek the advice of an independent insurance agent to help you make sense of the coverages, deductibles, and loopholes within policies offered by various insurance carriers. An independent agent is uniquely positioned to help you find the best policy for your needs and budget because he or she represents multiple competing carriers, rather than just one. Don’t rely solely on an insurance company’s reputation or marketing. Instead get the facts so you can make an informed purchase.
We Can Help
Are you and your family in a precarious position? Arrange for a homeowner’s insurance review with an independent agent. Why not make an appointment today? You’ll sleep better knowing you did the smart thing. Call us at (800) 947-1270 or (610) 775-3848, or click below to contact us.
 As the owner of a commercial building, any permanent upgrades made to your property by a tenant become your property, not the tenant’s property. This may seem obvious, but consider the impact should damage be done to such improvements during the tenant’s leasing period. Whose insurance will pay for the repair or replacement cost? Will either insurance policy pay? Will both pay? Can you live with the uncertainty of not knowing?
 Providing workers compensation insurance for employees can be a significant expense, especially in industries prone to serious injuries, such as those requiring heavy or potentially dangerous machinery. While some employers may be tempted to misclassify workers as independent contractors rather than as employees in order to avoid worker’s comp insurance and other costs, the penalties for misclassifying employees as independent contractors can be severe.
 Having the proper business insurance can be vital to growing your company and protecting your future. While every business varies in terms of exposure to risk and the related cost of coverage, knowing the 5 key cost drivers can help you reduce your insurance costs, whether you are in a mid-sized city like Reading or Allentown, a smaller city like York or Lancaster, or a large city like Philadelphia, especially if you consider costs before launching your business.
 Ah, but think of it this way: wouldn’t it be great to have the peace of mind of knowing that you are financially covered against many of the uncertainties life can throw at you? Isn’t that better than the nagging feeling that you may be unprotected against some unknown liability for which you failed to get the needed business insurance protection?

 Are You at Risk?
 5 Easy Steps to Better Public Liability Insurance Protection & Greater Savings:
 An affordable policy can help you save money without straining your budget. Here are seven tips to help you pay less for insurance:
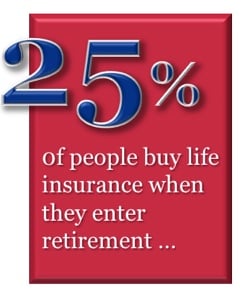 With the large baby boom generation entering retirement age, retirement planning is getting more and more attention. Interestingly, while marriage is still the leading cause for people to buy life insurance, retirement is also a major motivation. In fact, research from Northwestern Mutual Life, as conducted by Harris Interactive, shows that 25 percent of people buy life insurance products when they enter retirement -- almost as much as the 32 percent of people that buy it after getting married.