Insurance Savings and News You Can Use
Join the Conversation!

Small Business Insurance Costs and the Affordable Care Act

Posted by David Ross on Tue, Apr 22, 2014

Business health insurance cost predictions under Obamacare (AFA) according to the Center for Medicaid ServicesHow Will the Affordable Care Act Affect Small Business Health Insurance Costs?

You would have to be living on a desert island or under a rock not to have heard of the Affordable Care Act (a.k.a. Obamacare).  But with all the partisan arguments about how wonderful or – conversely - how awful this new law is, it’s hard to separate the wheat from the chaff.  So, as Sgt. Joe Friday said, we’ll try to stick with "just the facts, ma'am."

Affordable Care Act Facts:

FACT: The Affordable Care Act (ACA) was passed by Congress and then signed into law by President Obama on March 23, 2010. 

FACT: On June 28, 2012 the Supreme Court rendered a final decision to uphold the health care law.

FACT: Open enrollment in the Health Insurance Marketplace began October 1, 2013 and ended March 31, 2014

That’s probably where the “facts” end.  The stated intent of the ACA was to offer affordable health insurance to every American.  According to the U.S. Department of Health and Human Services website, the ACA “puts consumers back in charge of their health care. Under the law, a new ‘Patient’s Bill of Rights’ gives the American people the stability and flexibility they need to make informed choices about their health.”  Few would argue with the value of the law’s stated goals, which are summarized as follows on the HHS website: “All together, these reforms mean that millions of people who were previously uninsured will gain coverage, thanks to the Affordable Care Act.”

What Impact Will the Affordable Care Act Have on Small Business Insurance Costs?

The full repercussions of the ACA on small businesses and their health insurance costs – and whether it’s truly “wonderful” or actually “awful” - won’t be known for several years; however, the Center for Medicare and Medicaid Services (CMS), which spearheaded the implementation of the law, presented a report to congress with a few predictions.  In the interest of “sticking with the facts,” CMS’s report states, “There is a rather large degree of uncertainty associated with this estimate. The impact could vary significantly depending on the mix of firms that decide to offer health insurance coverage.”

CMS: 2/3 of Small Businesses to See Increased Costs

A recent Small Business Association poll found that 96 percent of small businesses said their health insurance premiums have significantly increased over the past five years, with average monthly insurance costs increasing from $590 per employee in 2009 to $1,121 in 2014.  CMS’s research indicates those rates will continue to rise.  The CMS report states that the new rules, such as requiring that insurers offer guaranteed health coverage and insurance renewal options to small employers and preventing insurance companies from varying their rates based on a company’s industry or the age of its employees, will most likely drive up the price of insurance for many small businesses. 

The report estimates that 65 percent of small businesses are expected to experience increases in their premium rates, while only 35 percent will see a reduction. Businesses with exceptionally sick or at-risk workers will benefit most from the new provisions.  The effect on large employers is expected to be negligible, since many larger companies run their health insurance programs in house. 

What Can You Do to Control Your Business’s Health Insurance Costs?
Affordable Care Act and Your Health Insurance: Get our free fact sheet and get the information you needAmerican Insuring Group can help you navigate through the complexities of the new ACA rules and ensure that you get the best health insurance premiums available.  Contact an agent at (800) 947-1270 or (610) 775-3848 for more information about health insurance and the Affordable Care Act.

Want to learn more? Download our free report: 10 Things You Should Know About Health Insurance Under the Affordable Care Act
Tags: Health Insurance Reading PA, Health Insurance Allentown, Health Insurance Harrisburg, Small Business Insurance, Small Business Insurance Reading PA, Affordable Care Act, Health Insurance, Health Insurance Berks County, Health Insurance Philadelphia, Health Insurance Lancaster

Home Prices Are Up. Do You Need More Homeowner's Insurance?

Posted by David Ross on Tue, Mar 25, 2014

House prices are up. Should your house insurance coverage rise too? Tips on homeowner's insurance from American Insuring Group, serving Reading, PA, Philadelphia, Lancaster, York, Harrisburg, Allentown, Bethlehem, Pittsburgh, Erie, Pennsylvania and beyond with quality house insurance for over 25 years.2013 was a good year for the real estate industry.  The price of homes increased by more than 20% in certain hotspots, and experts predict that home prices will continue to rise in 2014 – albeit, at a more moderate rate of 3-5%.  This is great news if you’re a realtor or if you’re trying to sell your home.  But you might be asking yourself, “Does this mean I need to reevaluate the insurance coverage on my home?  Does this mean I have to pay higher house insurance premiums?”
Market Value vs. Replacement Cost Value

Before we answer this question, you need to understand the difference between “market value” and “replacement cost value.”  Market value is how much you should be able to get for your home if you were to sell it.  This value is based on location, the value of the land, and other real estate trends. On the other hand, replacement cost is what it would cost to replace your home if it was completely destroyed – if you had to rebuild it from the ground up. 

Why Did You Purchase Homeowner’s Insurance?

Now think about why you purchased your homeowner’s insurance.  Wasn’t it to protect you and your family against unforeseen disasters?  If a storm rips the roof off your home, you want to be able to replace it.  If your house is completely destroyed by a fire, you need to have the resources to rebuild it, so you and your family have a place to live.  Plus, most disasters that can affect your home don’t affect the land itself.  If a tornado blows through your home or a tree lands on your roof, the value of the land your home rests on isn’t affected. 

Therefore, you should insure your home for what it would cost to repair or replace it, not what someone else would pay for it.  So, if the market value of your house increases because of the real estate market, there’s no need to re-evaluate your homeowner’s insurance.  Plus, most homeowner’s insurance policies have an inflation guard that automatically increases the value of the property by 3-5%.

When Considering Insurance on Your Home, Remember the Upgrades!

Now, if you make improvements to your home, such as an addition or a major renovation, it can affect both the market value and the replacement cost.  In that case you should contact your insurance agent, so you can make sure that your entire investment is protected in the event of a disaster. 

Get a free homeowner's insurance quoteIf you’d like to take a look at your homeowner’s insurance to be certain your home has sufficient protection, contact American Insuring Group at (800) 947-1270 or (610) 775-3848. We'll help you get the right level of quality insurance at the right price, quoting several competing insurance providers in the process.

Tags: House Insurance Reading PA, Homeowners Insurance Lancaster Pa, House Insurance Allentown Pa, House Insurance Lancaster Pa, Homeowners Insurance Philadelphia Pa, House Insurance, Homeowners Insurance, Homeowners Insurance Allentown Pa, Homeowners Insurance Reading Pa, House Insurance Philadelphia Pa, Homeowners Insurance Harrisburg PA, Homeowners Insurance York PA

8 Easy Ways to Lower Your Life Insurance Premiums

Posted by David Ross on Sat, Mar 15, 2014

Tips for making life insurance more affordable. By American Insuring Group, serving Philadelphia, PA, Reading, Allentown, Bethlehem, Harrisburg, Pittsburgh, Erie, Lancaster, Lebanon, Hershey, York, Pennsylvania and beyond.Have you ever wondered what factors determine your life insurance rates?  Is it just your age…the state of your current health? Is there anything you can do to make your life insurance more affordable?

Insurance companies look at several factors to determine the likelihood that A) you’ll live a very long life, or B) you’ll die very soon. As depressing as that may sound, it’s a fact, and it’s what determines your life insurance premium. 

What Do Life Insurance Companies Consider When Setting Your Premium?

While every insurance company has its own underwriting criteria to determine your premium, you may be surprised by some of the factors they look at.  What isn’t surprising is that many of the factors that determine your life insurance premiums can also affect the quality and/or length of your life. Some you can change and some you can’t.  

Here are eight factors many insurance companies use to determine your life insurance premiums, and some tips on how to get a better rating and save on your life insurance policy.

1. Driving violations

If you’ve had two moving violations in the past year or a DUI in the past 5 years, you may be considered a reckless driver, which could put your life in danger and pose more risk for the insurance company.  There isn’t much you can do about existing violations, but you can SLOW DOWN and not drink and drive.

2. Your workplace colleagues

If you have group life insurance from your workplace, the premiums are based on the average age and health of everyone, not just you.  So if you work with a group of individuals who are older and less healthy than you, it may raise your premium.  On the other hand, if you work with a group of individuals who are younger and healthier than you, it may lower your premium.  Make sure you compare the price of an individual health insurance policy before jumping into a group plan. 

3. Credit history

Individuals who have filed for bankruptcy are considered a high-risk proposition and many insurance companies won’t even issue a policy until their credit report has been cleared. Make sure you consider all the alternatives and consequences before filing for bankruptcy. 

4. Lifestyle

Are you a daredevil?  Do you prefer skydiving to reading…car racing to gardening? Certain hobbies can disqualify you from getting the best rate on life insurance.  Even travel outside of the country can increase your premiums.  So, consider the increased cost of life insurance when weighing the pros and cons of your career choices.

5. Occupation

Higher-risk occupations, such as airline pilots and high-rise construction engineers, can create a higher risk for premature death, thereby causing higher life insurance premiums.  Solution – choose your occupation wisely.

6. Smoking Habits

We all know smoking can raise your risk of stroke, lung disease and many other life-threatening medical conditions; therefore insurers often charge smokers a higher premium.   One more reason to kick the habit. 

7. Your weight

There are a number of diseases related to being overweight that can shorten your lifespan.  Most insurers look at height, weight, and body mass index (BMI) to determine your premium.   Plus, many insurers want to see you keep that weight off for at least one year before they will offer you a better rate.   So if you were looking for that final push to get you started on an exercise and diet plan, think about all the money you can save on your life insurance premiums.

8. Family health history

Your family’s medical history shows what diseases you may be prone to. You can choose your friends, but not your family; however, you can choose to protect your family with the right level of life insurance, and you can ask your doctor for advide on how you may be able to reduce your health risks through proper diet, exercise, and other factors in light of your family medical history.

Contact American Insuring Group near Reading, PA for help in finding the right life insurance policy for your business or family.Ready to Talk Life Insurance?

Contact American Insuring Group at (800) 947-1270 or (610) 775-3848 to learn more about your life insurance options, or for a free quote on life insurance.

Tags: Life Insurance Berks Pa, Life Insurance Philadelphia Pa, Life Insurance Lancaster Pa, Life Insurance Reading PA, Life Insurance Allentown Pa, Life Insurance Harrisburg Pa, Life Insurance York Pa, d Life Insurance, Life Insurance

How Health Insurance and Other Benefits Can Help Your Bottom Line

Posted by David Ross on Sat, Mar 08, 2014

Providing employee health insurance and other benefits helps retain top talent. Do you believe employees are your most valuable asset? Contact us today for affordable employee benefits like health insurance, life insurance, and workers compensation insurance. We serve Philadelphia, Reading, Lancaster, Allentown, York, Lebanon, Pittsburgh, Erie, PA and beyond.Do you believe that your employees are one of your most valuable assets?  Do you think of your employees as an investment rather than an expense?  
The fact is that happy, engaged, and loyal employees work harder, provide better customer service, and stay with you longer. That's why great benefits, especially health insurance, can be crucial to attracting and retaining the best employees.

Consider these facts:

  • The average cost of recruiting, hiring and training a new employee is close to $4,000, according to an article in Entrepreneur Magazine.
     
  • The companies listed on Fortune’s ‘100 Best Companies to Work For’ list experienced stock prices that rose an average of 14% per year from 1998-2005, compared to 6% for the market as a whole, according to a study from the Jackson Organization. That's more than double the norm, and suggests a strong link between employee satisfaction and company performance.

If you truly value your employees, it's important to do more than just say that you value them, so prove it to them via their health insurance, life insurance, and other benefits!  If you don’t show you care about their needs, they'll be less motivated to care about your company or their work, and your bottom line will suffer as a result.  If you want to stand out as an employer and attract real talent, it’s important to do what you can to ensure that your employees are healthy and happy – both physically and financially.

Start with a Good Employee Benefits Package

A good employee benefits package is a great place to start.  Unfortunately, during these rocky economic times, many companies are tempted to cut employee benefits.  This “cost-saving” measure will most likely backfire on you by creating less motivated employees and a higher turnover rate.

Mandatory Employee Benefits

While some benefits are optional, all employers are required to provide employees with the following benefits:

  • Give employees time off to vote, serve on a jury and perform military service.
  • Comply with all workers' compensation requirements.
     
  • Withhold FICA taxes from employees' paychecks and pay your own portion of FICA taxes, providing employees with retirement and disability benefits.
     
  • Pay state and federal unemployment taxes, thus providing benefits for unemployed workers.
     
  • Contribute to state short-term disability programs in states where such programs exist.
     
  • Comply with the Federal Family and Medical Leave Act (FMLA).

Providing additional benefits, such as health insurance, dental, vision, and life insurance plans will attract better-qualified candidates, ensure higher retention rates, and increase your bottom line. 

We Can Help You Craft a Better Employee Benefits Package

Contact us for help in crafting a better employee benefits package that includes health insurance and life insurance.Contact American Insuring Group at (800) 947-1270 or (610) 775-3848 to discuss affordable health, life, and workers compensation insurance plans to make yours a better company that attracts and retains the high-caliber talent you need to excel in the marketplace.

Tags: Workers Compensation Insurance, Health Insurance Reading PA, Health Insurance Allentown, Health Insurance Harrisburg, Employee Benefits, Health Insurance, Health Insurance Berks County, Health Insurance Philadelphia, Health Insurance Lancaster, Commercial Insurance, Business Insurance

Health Insurance & ObamaCare: 10 Facts You Should Know

Posted by David Ross on Thu, Feb 27, 2014

10 health insurance facts you need to know about ObamaCare - The Affordable Care ActThere is a lot of uncertainty these days regarding what is required under the Affordable Care Act, also known as ObamaCare. Businesses and individuals alike are concerned they may be penalized or miss out on important information needed to keep their health insurance in tact and affordable.  
With that in mind, here are 10 things you should know:

  1. As of January 1st 2014, every person must be insured under a Qualified Health Insurance Plan.
     
  2. If Employer Coverage is not offered, it is the responsibility of the Individual to purchase insurance independent of their Employer.
     
  3. If a person is not insured in 2014, they will be faced with an Individual Tax penalty equal to $95/person or 1% of your taxable income…whichever is greater!
     
  4. The Initial Open Enrollment period ends March 31st, 2014.
     
  5. Health plans sold after January 1, 2014 must include a list of 10 Essential Health Benefits such as Maternity coverage, Mental Health coverage, Prescription coverage, Pediatric Dental coverage, etc.
     
  6. Health Plans will fall into 4 Metal Levels (Platinum, Gold, Silver, Bronze) and also include a catastrophic coverage option for those under 30 or for those meeting specific hardship guidelines.
     
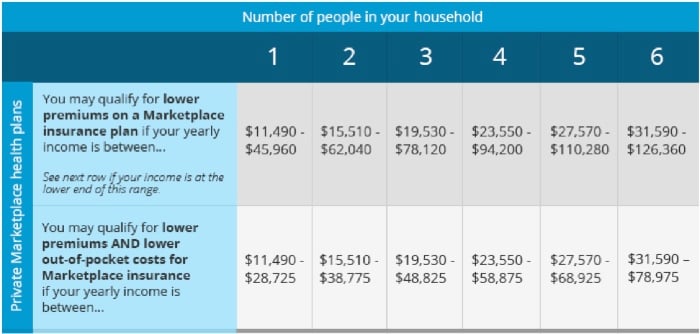
  7. There is premium assistance for people making between 100-400% of the Federal Poverty Level.
     
  8. In addition to premium assistance, there are cost sharing subsidies (reduction in deductibles and out-of-pocket expenses) for those between 100-250% of the Federal Poverty Level.
     
  9. The only way to claim the Premium Subsidy (Advance Premium Tax Credit) and the Cost Sharing Subsidies is to apply with the Federally Facilitated Marketplace (FFM).
     
  10. Because the FFM is temperamental, the best way to apply and evaluate your coverage options is to contact a CERTIFIED Licensed Producer for assistance.
Please note: There is not an increase in cost if you choose to use a Certified Licensed Producer.
Here is a handy chart to help you determine if you are eligible to receive a premium subsidy.
Summary of health insurance premium assistance under ObamaCare Affordable Care Act


Contact us to obtain affordable, high quality health insurance for your employees or family. We supply health insurance coverage for Reading, PA, Berks County, Philadelphia, Lancaster, Lebanon, Allentown, York, Harrisburg, Pittsburgh, Bethlehem, Erie, and all of Pennsylvania and beyond. Contact us for a free quote.Looking for help in obtaining the right health insurance coverage for your employees or family?

Contact us today at American Insuring Group or request a free health insurance quote.

Tags: Health Insurance Reading PA, Health Insurance Allentown, Health Insurance Harrisburg, Health Insurance, Health Insurance Berks County, Health Insurance Philadelphia, Health Insurance Lancaster

Business Insurance for Heavy Equipment: What You Should Know

Posted by David Ross on Thu, Feb 27, 2014

Get commercial insurance protection for your heavy construction equipment like tractors, forklifts, and backhoes. We insure construction firms in Reading, PA, Philadelphia, Allentown, Harrisburg, Lancaster, Pittsburgh, Erie, PA and beyond. Call today for a free construction insurance consultation.If your business requires the use of heavy equipment - such as tractors, backhoes, and forklifts – chances are a large percentage of your business assets are tied up in that equipment, making the protection of that equipment from damage or loss a high priority for you and your business. 

According to the 2012 Equipment Theft Report from the National Insurance Crime Bureau (NCIB), the total value of stolen equipment in 2012 was close to $300 million.  Those numbers don’t include losses from business interruption, project-delay penalties, and wasted workforce time. 

Here are some eye-opening statistics from the NCIB report:


  • In 2012, a total of 10,925 heavy equipment thefts were reported to law enforcement in the U.S.
     
  • Texas ranked number one in 2012 with 1,401 reported thefts. In second place was North Carolina with 1,037 thefts, followed by Florida in third with 890 thefts. 
     
  • The three most stolen heavy equipment items in 2012 were mowers (riding or garden tractor: 5,363), Loaders (skid steer, wheeled: 1,943), and Tractors (wheeled or tracked: 1,459).
     
  • Heavy equipment manufactured by John Deere was the number one theft target in 2012 followed in order by Kubota Tractor Corp., Bobcat, Caterpillar and Toro.
     
  • Most often, equipment was stolen from a work site where there is usually less physical security.

A Poor Recovery Rate Means Construction Company Insurance for Heavy Equipment is Critical

Perhaps the most alarming statistic in the report was the recovery rate - “Of the 10,925 reported equipment thefts in 2012, [the National Crime Information Center] NCIC reported 2,204 recoveries.”    With a 20 percent recovery rate, the loss of stolen equipment is costly to insurance companies and equipment owners alike.  In fact, theft is the most frequent cause of heavy equipment loss. 

Theft Prevention Strategies

The good news is that in addition to protecting your equipment with the appropriate insurance, there are also measures you can take to significantly decrease the chance of a theft in the first place.  Here are some theft prevention strategies from the NCIB. 

  • Install hidden fuel shut-off systems.
     
  • Remove fuses and circuit breakers when equipment is unattended.
     
  • Render equipment immobile or difficult to move after hours or on weekends by clustering it in a “wagon circle.” Place more easily transported items, such as generators and compressors, in the middle of the circle surrounded by larger pieces of equipment.
     
  • Maintain a photo archive and a specific list of the PIN and component part serial numbers of each piece of heavy equipment in a central location. Stamp or engrave equipment parts with identifying marks, numbers, or corporate logos.
     
  • Use hydro locks to fix articulated equipment in a curved position, preventing it from traveling in a straight line.
     
  • Use sleeve locks to fix backhoe pads in an extended position, keeping wheels off the ground.

Play it Smart: Insure Your Heavy Equipment

Call us today to get insurance for your heavy equipmentSince no amount of prevention will stop every thief, it’s important that you contact an American Insuring Group agent at (800) 947-1270 or (610) 775-3848 to make sure that you have the right insurance for your expensive heavy equipment in the event of a theft.
Tags: Construction Equipment Insurance, Commercial Insurance Allentown PA, Commercial Insurance Lancaster PA, Commercial Insurance Harrisburg PA, Heavy Equipment Insurance, Commercial Insurance, Commercial Insurance Reading PA, Business Insurance, Commercial Insurance Philadelphia PA, Commercial Insurance Berks County

Forget the Past, Look to the Future: Get Life Insurance

Posted by David Ross on Sat, Feb 15, 2014

Plan for the Future with Life InsuranceA new year is a great time for reflection and fresh starts.  It’s the perfect time to put the past behind you and look toward the future.  Compared to losing those extra 20 pounds, protecting your family in the event of a death is a surprisingly easy New Year’s resolution. 

Although most people don’t want to think about their own death or the death of a loved one, preparing for the event is one of the most selfless acts you can do for your family. 

Life Insurance for the Primary Breadwinner

The first thing you want to do, if you haven’t already, is ensure that the primary breadwinner in the family is covered.  Nothing can replace a spouse or a parent, but the financial consequences of that loss are another matter.  Life insurance can protect the surviving family members from the loss of future income and the expenses that occur as a result of a death.  Most people understand the importance of life insurance for the primary breadwinner, but there are other considerations as well.

Life Insurance for your Spouse

Very few families today can survive on one income, so even if a spouse makes less than the primary breadwinner, you should take a look at what the loss of that income would mean to your family.  Could you survive financially if you lost that second income?  Or, let’s say that spouse doesn’t produce a monetary income, but he or she is the primary caregiver of children or aging parents.  What would it take, financially, to replace that care?  No, life insurance can never replace the love of that caregiver, but it can give the survivors some peace of mind that their essential needs will be taken care of.

Life Insurance for your Children

Finally, the death of a child is probably the worst thing that can happen to anyone, and it’s every parent’s worst nightmare.  It’s something no parent wants to even consider, but in the event that something should happen, life insurance can at least alleviate the financial burden of a child’s death.  Many people believe that purchasing life insurance for children is a giant waste of money.  Your children probably aren’t bringing home a paycheck that you rely on to pay the bills, but there are other factors to consider.  

  • The average cost of a traditional funeral is almost $6,600, according to the National Funeral Directors Association. Cemetery services, including the gravesite and vault or liner, can cost an additional $3,000.  A life insurance policy on your child allows parents to grieve without the burden of worrying about how they will pay for the funeral.
     
  • Medical bills left from a prolonged sickness and/or emergency room visits can accumulate and become a burden to a family mourning the loss of a child.  A National Institute of Health (NIH)-funded study found the average cost for an ER visit was more than $2,000. In 2012, 11 of the 12 FDA-approved drugs for cancer were priced above $100,000 for a year of treatment.
     
  • Your child may develop a condition later in life that will preclude them from purchasing life insurance in the future.  Protecting your child early in life can ensure they have protection in the future.

Protect Your Family with the Right Life Insurance

Look to the future: protect your family with the right life insuranceLooking to the future by protecting your family with life insurance is one of the easiest and most selfless resolutions you can make.  Make it a goal to protect your family with the right life insurance.  Contact us at American Insuring Group at (800) 947-1270 or (610) 775-3848 to learn more about affordable life insurance policies available for your entire family. 
Tags: Life Insurance Berks Pa, Life Insurance Philadelphia Pa, Life Insurance Lancaster Pa, Life Insurance for Children, Life Insurance Reading PA, Life Insurance Allentown Pa, Life Insurance Harrisburg Pa, Life Insurance York Pa, Life Insurance

Business Insurance and Your New Year's Resolutions

Posted by David Ross on Tue, Feb 11, 2014

Did you remember business insurance when making your new year's resolutions? Here is why you should have.Be honest!  Did you make any New Year’s resolutions this year?  If you did, you weren’t alone.  According to Statistic Brain, 45% of Americans “usually” make New Year’s resolutions, and according to Constant Contact®, 53% make business-related resolutions. 
Statistic Brain found that losing weight is the number one New Year’s resolution for 2014 – no surprise there.  And number two?  The second most popular resolution for 2014 is – drum roll please - getting organized.  Now if losing weight is on your list, there are many other organizations more suited to helping you than an insurance company (unless you want to know how weight could possibly affect your life insurance premiums).  However, a good insurance agent can help get your business organized.

Getting organized isn’t just about “A place for everything, everything in its place,” as Benjamin Franklin said.  It’s also about having everything you need so your business can run smoothly and profitably.  The right business insurance can help your business do just that - and protect it by minimizing financial risks associated with unexpected events.

Commercial Liability Insurance

First, you should consider liability insurance to protect your company’s assets in the event that someone gets hurt on your property or you (or one of your employees) cause property damage or injury.  Even if you doubt you’ll ever face a claim, we live in a litigious society; purchasing liability insurance is a wise and affordable investment.  There are a wide variety of commercial liability insurance options such as general liability insurance, product liability insurance, and error and omission insurance. 

Commercial Property Insurance

Commercial Property Insurance is another insurance to consider.  It covers everything related to the loss or damage of company property due to events such as fire, windstorm and hail, smoke damage, vandalism, theft, and more. “Property” may include lost income, business interruption, and company papers, as well as equipment and buildings.

Commercial Vehicle Insurance

If you use a vehicle – whether you own it or not – for any purpose other than driving to and from work, you should check your existing insurance policy to see if you need a commercial vehicle policy.  Standard vehicle insurance coverage includes bodily injury and property damage liability, personal injury protection, and physical damage to your vehicle including comprehensive and collision coverage. 

Worker's Compensation Insurance

Worker’s Compensation Insurance is mandatory in most states (including Pennsylvania), and covers employees for work-related injuries.  A typical "workers comp" insurance policy pays lost wages and medical expenses incurred due to a work-related accident and protects the employer against accident-related lawsuits.  

Business Umbrella Insurance

Finally, umbrella liability insurance is a type of commercial insurance that covers a small business for liability claims that exceed the underlying limits of liability coverage.  Umbrella policies are a type of commercial insurance that adds an extra layer of public liability insurance protection.  

Today is the time to review your business insurance needs. We help customers with all types of commercial insurance, from Reading, PA to Philadelphia, Allentown, Lancaster, Harrisburg, York, Erie, Pittsburgh and points in between. Call us today for a no-risk analysis of your business insurance needs.Now is a Great Time to Review Your Business Insurance Needs

Whether “getting organized” is on your list of 2014 New Year’s resolutions or not, now is a great time to review your insurance policies to ensure that you have the right coverage to protect your business and allow it to run smoothly.  AIG would be very happy to help you with this resolution.  Contact us at (800) 947-1270 or (610) 775-3848 to arrange a policy evaluation.  Then you can sit back and enjoy your well-ordered office space, knowing that it’s protected.

Unfortunately, you’ll have to call someone else if you want help losing weight!


Tags: Umbrella Liability Insurance, Workers Compensation Insurance, Commercial Vehicle Insurance, Umbrella Insurance, Commercial Insurance, Business Insurance, commercial property insurance

Key Person Life Insurance and Million Dollar Legs

Posted by David Ross on Thu, Feb 06, 2014

What do Legs Have to do with Key Person Life Insurance?

WLearn why key person insurance may be right for your business. We insure large and small businesses in PA, including Reading, Philadelphia, Harrisburg, Erie, Lancaster, Allentown, Hershey, York and beyond. Call for the best advice on key person life insurance.e’ve all heard stories about celebrities insuring various body parts for ridiculous sums of money - most famously, Betty Grable’s legs were insured for a million dollars. Why would anyone insure such a thing? The fact of the matter is, her studio made a lot of money off of Betty Grable’s appearances, and a large part of her appeal were her fabulous gams. If her legs had been marred in any way, her ability to sell movies and posters would’ve been greatly reduced.   

Now, think about this.  Are there any parts – such as key person - of your business that, if lost, would significantly impact your bottom line?

Who is a Key Person?

A key person in your company is like Betty Grable’s legs. That person could be one of your executives, your best salesperson, your gem of an office manager who keeps things running smoothly, or an old hand who knows where all the skeletons are buried (figuratively, of course!). A key person is any employee who, if he/she suddenly passed away or became unable to work, would cause your business to struggle. Look around your office – who couldn’t your business afford to lose?

The Vulnerability of Small Businesses and the Need for Key Person Insurance

Getting Key Person Life Insurance is especially vital for small businesses, both because they generally have a thinner line between success and failure, and because they have smaller workforces. A giant firm with offices all over the country may not have any employees who are irreplaceable; since they are all tiny cogs in a giant machine with many redundancies, while a small company with only a few employees has less overlap in responsibilities.

With a small workforce, employees often have unique and specialized knowledge and connections that may not be easily replaced. Also, for businesses just starting out, if one of the partners has an accident, the poor fledgling company would be doomed to fail unless there was some kind of cushion. That cushion could be a Key Person Life Insurance policy.

Grieve without the Worry

Of course, the loss of any employee’s life - regardless of how essential they were to your business - is an awful thing to contemplate. A Key Person Life Insurance policy can allow you to grieve, without the worry of how you’re going to be able to keep the company afloat until you find or train a replacement.

Is Key Person Life Insurance Right for Your Business?

Is key person insurance right for your business? Call us for answers.If you have people who are as valuable to your business as Betty Grable’s legs were to her, contact American Insuring Group at (610) 775-3848 or (800) 947-1270 for information on Key Person Life Insurance policies for your business!
Contact us to learn more about Key Person Insurance. We serve Philadelphia, Reading, Lancaster, Allentown, Harrisburg, Pittsburgh, Erie, Scranton, and all of Pennsylvania and beyond with quality business insurance at affordable prices.

Tags: Small Business Insurance, Commercial Insurance Allentown PA, Commercial Insurance Lancaster PA, Commercial Insurance Harrisburg PA, Key Person Insurance, Commercial Insurance Reading PA, Business Insurance, Commercial Insurance Philadelphia PA, Commercial Insurance York PA, Commercial Insurance Berks County, Life Insurance

Is Long Term Care Insurance Right for You?

Posted by David Ross on Sat, Jan 11, 2014

Tips for considering long-term care insurance. We serve Reading, Lancaster, Philadelphia, Allentown, Harrisburg and beyond with health insurance protection. Contact us for a free consultation.Do you want to become a burden to your family? Of course not.
Do you have homeowner’s insurance to protect your home in case of a fire?  Chances are you do.  It’s a very scary thought and – wisely - very few people think twice about protecting themselves against such a possibility. 

Less Than 8% of Adults Have Long Term Care Insurance: Why?

OK, next question… Do you have long term care insurance (LTCI)?  There’s a good chance that your answer is no.  Recent statistics show that less than 8% of U.S. adults and about 10% of seniors have long-term care insurance.  And yet, nearly 10 million people in the U.S. (37% under age 65 and 63% over age 65) needed some form of long-term care in 2000 (see http://longtermcare.gov/ for more information).  It’s estimated that almost 70% of people turning age 65 will need long-term care at some point in their lives. 

Bottom line… Your chances of needing to make a claim for long-term care are considerably higher than making a claim for a fire.

What Exactly is Long Term Care Insurance?

LTCI helps pay the cost of care for seniors or individuals with disabilities if they should ever need it over a long period of time.  It helps pay for the cost of care for individuals unable to perform the basic activities of daily living (ADLs) -- such as bathing, eating, getting in and out of bed, dressing, and going to the bathroom – over a long period of time. 

Depending on the policy, LTCI may cover home care, assisted living, adult daycare, respite care, hospice care, nursing home, and Alzheimer's facilities. Certain policies will pay for a visiting or live-in caregiver, companion, housekeeper, therapist or private duty nurse.

The cost of an LTCI policy is based on:

  • Your age when you purchase the policy
  • The maximum amount that a policy will pay per day
  • The maximum number of days/years that a policy will pay
  • Any optional benefits you choose, such as benefits that are adjusted for inflation

What is the Cost of Long-Term Care and Who Pays for it if You Don’t Have LTCI?

According to the U.S. Department of Health and Human Services, in 2010 the average cost for long-term care was more than $6,000 per month in a nursing home, more than $3,000 per month in an assisted living facility, or $19-$21 per hour for a homemaker or home health aide. 

One of the biggest misconceptions about long-term care is that it’s covered by Medicare.  Medicare only pays for a maximum of 100 days if you need skilled services or rehabilitative care in a nursing home.  It does not pay for non-skilled assistance with Activities of Daily Living (ADL), which make up the majority of long-term care services. 

Medicaid pays the largest share of long-term care services, but only applies if your income is below a certain level and you meet minimum state eligibility requirements.

Other federal programs such as the Older Americans Act and the Department of Veterans Affairs pay for long-term care services, but only for specific populations and in certain circumstances

Benefits of Long-Term Care Insurance

More and more people are purchasing LTCI to protect themselves in the event that they need long-term care.  Some of the benefits include:

  • Ensuring that you will be taken care of should you need long-term care
  • Allowing you to live as independently as possible without burdening your family 
  • Allowing you to spend family time with your children rather than caregiver time
  • Protecting your savings
  • Premiums paid on a long-term care insurance product may be eligible for an income tax deduction

Learn More about LTCI

Contact us to learn more about long-term care insurance for you or your loved ones.If you want to ensure that you can live independently and not become a burden to your family and friends in the event that you need care over a long period of time, give us a call at (800) 947-1270 or (610) 775-3848 or contact us by email.  The sooner the better!
Tags: Health Insurance Reading PA, Health Insurance Allentown, Health Insurance Harrisburg, Long Term Care Insurance, Health Insurance, Health Insurance Berks County, Health Insurance Philadelphia, Health Insurance Lancaster